-
What Are the Most Advanced Technologies Being Developed Today And What Do They Mean for Investors?
In a world undergoing unprecedented technological acceleration, a new generation of transformative technologies is fundamentally reshaping industries, economies, and societies. These innovations—ranging from artificial general intelligence to quantum computing, synthetic biology, brain-computer interfaces, and beyond—represent not only massive leaps in scientific capability but also entirely new paradigms for how humans interact with the world around them.
For investors, these breakthroughs are not merely exciting; they are essential. The ability to identify, understand, and fund the right technologies at the right stage can determine the winners and losers of the next economic era. Yet, frontier tech investing also brings challenges: high uncertainty, long R&D cycles, regulatory hurdles, and often opaque commercialization paths.
This article offers a comprehensive review of the most advanced technologies in development today, a breakdown of their fund stage dynamics (Seed to Growth), and a cross-sector investment thesis tailored to their unique risk/return profiles. It’s designed for sophisticated investors looking to engage with innovation that will define the next decade.
Advanced Technologies: Sector-by-Sector Overview
1. Artificial General Intelligence (AGI) & Foundation Models
- Stage: Series A–Growth. Industry leaders like OpenAI and Anthropic are raising late-stage rounds, but supporting infrastructure—like fine-tuning platforms, vector databases, and safety layers—are entering Seed and Series A.
- Thesis: Focus on verticalized AI tools (e.g., AI for law, finance, or biotech), secure deployment frameworks, and foundational infrastructure. Favor companies with differentiated data access and explainability tools.
2. Quantum Computing
- Stage: Predominantly Seed–Series A, with selected companies at Growth (e.g., IonQ IPO). Still deep-tech with few scalable commercial applications today, but rapidly growing interest from enterprise and government sectors.
- Thesis: Prioritize companies building quantum software abstraction layers, developer platforms, and vertical use cases in chemistry, logistics, and encryption. Seek co-investments with defense primes and scientific consortia.
3. Synthetic Biology & Biomanufacturing
- Stage: Seed to Growth. Lab-stage R&D platforms are raising Seed, while scale-up firms (e.g., bio-CDMOs, enzyme producers) are moving toward Growth rounds.
- Thesis: Look for scalable, repeatable bioprocesses. Focus on product platforms that leverage programmable biology—particularly in sustainable materials, therapeutics, and industrial fermentation. Consider public-private infrastructure alignment.
4. Space Technologies & LEO Economies
- Stage: Seed to Growth. Satellite analytics and software are Series A–B. Space manufacturing, debris management, and biotech in microgravity are typically Seed.
- Thesis: Avoid high-CAPEX launch players unless vertically integrated. Invest in data, software orchestration, and edge-processing platforms. Future-proof with dual-use potential (civil + defense).
5. Brain–Computer Interfaces (BCIs)
- Stage: Seed–Series A. Invasive BCIs (e.g., Neuralink) are still in early clinical phases. Non-invasive applications (EEG, neurofeedback, brain monitoring) show faster adoption curves.
- Thesis: Focus on therapeutic applications: stroke rehab, paralysis, PTSD treatment. Favor companies with early FDA traction or that serve as platform tech for neurophysiology or diagnostics.
6. AI + Robotics (Physical Intelligence)
- Stage: Series A–Growth. Warehouse automation and co-bots are at commercial deployment; humanoid robotics still Seed or early Series A.
- Thesis: Back robotics companies that pair general-purpose LLMs with task-specific training. Invest where hardware, software, and data feedback loops are tightly integrated. Look for B2B sales with short payback periods.
7. Web3, ZK Tech & Decentralized Infrastructure
- Stage: Seed–Series A. The shift from consumer tokens to developer infrastructure and privacy-enhancing technologies has clarified the investable landscape.
- Thesis: Focus on zero-knowledge proofs (ZKPs), rollups, modular blockchain layers, and compliance-first DeFi. Avoid speculative applications unless backed by robust protocol teams.
8. Next-Gen Energy (Batteries, Fusion, Carbon Tech)
- Stage: Growth for solid-state batteries; Seed–Series A for carbon capture, hydrogen, and nuclear fusion. Timelines vary significantly by sub-sector.
- Thesis: Pair venture capital with climate-aligned grant funding. Invest in IP-rich, infrastructure-adjacent solutions that align with national climate targets or emerging carbon markets.
Cross-Sector Investment Thesis
Investing in frontier technologies requires a refined lens—one that accounts not just for technical promise, but for team capability, regulatory risk, capital intensity, and global strategic relevance. Across sectors, successful theses share several common principles:
- Technical Maturity: Fund companies post-proof-of-concept but pre-saturation. Look for validated core science with clear commercial pathways.
- Moats & Defensibility: Prioritize novel IP, first-mover regulatory positions, and proprietary datasets. Avoid commodity tech unless paired with a unique business model.
- Capital Efficiency: Favor platforms with built-in scaling multipliers (AI, synbio, Web3 infra). Be cautious with hardware unless it’s fully integrated into a service model.
- Market Tailwinds: Climate action, aging demographics, geopolitical resilience, and data sovereignty create macro demand that supports otherwise speculative tech.
- Exit Pathways: Look for optionality—public markets, industrial buyouts, sovereign-backed scale, or ecosystem-dependent acqui-hires.
Stage-Based Portfolio Strategy:
- Seed: Back deep-science founders with domain expertise, compelling technical milestones, and go-to-lab validation.
- Series A/B: Focus on derisking—market traction, regulatory milestones, manufacturing capability. Fund scale and partnerships.
- Growth: Invest where customer contracts, enterprise usage, or infrastructure lock-in drive platform dominance.
Final Thoughts: Navigating the Frontier
Frontier technology investing demands a level of conviction—and patience—that differs from traditional software cycles. The rewards are often transformative: entire categories reshaped, new ecosystems created, and defensible returns generated through IP, data, and network effects. But risk is equally present.
The right strategy blends:
- Fast-turn commercial wins (AI copilots, robotics-as-a-service)
- Strategic infrastructure (space data, synbio supply chains)
- 10-year moonshots (AGI, BCIs, fusion, decentralized sovereignty)
Ultimately, investing in these technologies isn’t just a financial decision—it’s a generational opportunity to fund the breakthroughs that will define our world.
-
The Global Horse Sporting Industry: Market Landscape, Investment Opportunities, and Tech-Enabled Development Strategy
Executive Summary
Horse racing and equestrian eventing comprise a global industry valued at over $400 billion, with deep roots in tradition, competition, culture, and economic impact. These sectors span the elite world of professional racing circuits, elite breeding and bloodstock markets, grassroots riding schools and youth programs, and international eventing competitions with Olympic and World Cup status. While established markets such as the UK, Japan, Australia, and the US have sustained growth through robust wagering systems and event broadcasting, the next generation of growth is coming from underinvested markets and digital transformation.
This article provides a global view of the equine sports ecosystem, exploring current market size and trajectories, regional dynamics, investment-ready sectors, and pilot-ready technologies. Particular attention is given to the Caribbean region, where the horse racing tradition remains culturally vibrant yet economically vulnerable after the disruptions of COVID-19. Opportunities in digital health tracking, remote wagering, live-streaming, and clinic modernisation offer clear pathways to sustainable reinvestment and scalable growth.
Global Market Overview
Horse Racing
- Global value reached $402 billion in 2022 and is projected to reach $794 billion by 2030, showing a robust CAGR of 8.9%.
- Key revenue generators include betting turnover, with Japan (€24B), Australia (€17B), Hong Kong (€13B), UK, and the US leading.
- New growth areas include international syndicate racing, digital broadcast rights, VIP hospitality, and market re-entry in the Middle East and Southeast Asia.
Equestrian Eventing & Training

- The equestrian training services market is valued at $3.18 billion (2024), expected to grow to $5.34 billion by 2033 (CAGR 5.9%).
- The global equestrian equipment market is valued at over $12 billion, with the apparel market alone reaching $2.84 billion.
- Europe remains the sector’s anchor, contributing more than €100 billion in combined annual economic impact, supporting 400,000+ jobs across training, breeding, transport, venue operations, and leisure riding.
Regional Breakdown & Market Opportunities
United Kingdom & Ireland
- The UK hosts world-class racing at Ascot and Cheltenham and premier eventing at Badminton and Burghley. Ireland maintains a strong breeding and export market.
- Investment potential lies in revitalizing underutilized racecourses, digitizing grassroots event circuits, and creating OTT content platforms.
- Clinic revenue potential: £3–5K/weekend with 40–60 riders; Facilities can generate £150K–£500K annually depending on services and reach.
Gulf Region (UAE, Saudi Arabia, Qatar)
- Region anchors high-profile racing (Saudi Cup, Dubai World Cup). These events have emerged as global landmarks with prize purses exceeding $20 million.
- Significant opportunities lie in health tech integration (digital passports), elite training academies, and high-end wagering and hospitality infrastructure.
- Government-led investment is active, with equestrian sport part of wider national tourism and sports diversification agendas.
United States
- A vast but fragmented ecosystem, from Churchill Downs and Keeneland to local showgrounds and amateur associations.
- USEA hosts 250+ events annually with 44,000 competitors; rising demand for schooling shows, coaching clinics, and livestream access.
- OTT monetization of grassroots events and health record integration (HIPAA-like compliance for animals) are emerging opportunities.
Australia & New Zealand
- Racing and breeding markets are mature and heavily bet-driven. However, interest is growing in clinics, school holiday riding programs, and rural showgrounds.
- The Melbourne Cup generates AUD $468 million in economic activity; smaller events are seeking ways to tap digital audiences and drive remote revenues.
Caribbean
- Deep-rooted cultural importance of racing, yet systems remain undercapitalized. COVID-19 exacerbated issues, halting major events and closing OTB networks.
- Caymanas Park (Jamaica) shut in 2020, reopening under strict restrictions. Barbados Gold Cup was canceled in 2021–2022 but revived in 2023.
- Regional opportunities include the digitisation of betting infrastructure, reinvestment in racing welfare (aftercare), and creation of livestream events for diaspora and tourism markets.
Investment Opportunities
- Premium Race Events & Hospitality Ventures
- Saudi Cup, Dubai World Cup, and Melbourne Cup offer luxury brand tie-ins and cross-border syndicate investments.
- VIP hospitality, multi-platform coverage, and on-site betting lounges increase monetization layers.
- Digital Betting Platforms & Remote Wagering
- Create regulatory-compliant betting apps for underexposed circuits (Caribbean, regional US, rural Australia).
- Leverage gamification, live odds, and peer-to-peer challenges to attract younger bettors.
- Digital Passports & Veterinary Records
- Introduce cloud-based and blockchain-anchored equine passports to consolidate health, performance, and travel data.
- Sync with FEI, USEA, and national vet databases to support compliance and competition eligibility.
- Hybrid Clinics & Community Coaching Networks
- Develop tech-enabled clinics that combine physical coaching with livestreamed masterclasses and AI-driven feedback.
- Revenue via subscriptions, elite access fees, and sponsorship from tack/apparel brands.
- OTT Livestreaming & Media Monetization
- Target grassroots and mid-tier events overlooked by traditional broadcasters.
- Offer freemium platforms with ad-support, subscriptions, and virtual meetups.
Strategic Partner Ecosystem
Technology & Analytics
- Arioneo, Equilab, Zebra Insights – equine wearables, GPS training systems, digital IDs.
Health & Veterinary
- Vet-CT, FEI Veterinary Division – compliance tracking, imaging, and telemedicine.
Media & Betting
- Racing Post, Equidia, TwinSpires, Horse & Country TV – distribution platforms and betting partnerships.
Associations & Governing Bodies
- FEI, British Eventing, USEA, CTA – regulatory alignment and pilot facilitation.
Pilot Plans by Use Case
A. Digital Passports & Health Systems
- Test in UAE or UK with blockchain + cloud integration.
- Key success metrics: onboarding % of horses, reduction in inspection delays, compliance consistency.
B. Remote Wagering Platforms
- Launch in Caribbean (Barbados, Jamaica) and Australia’s rural circuits.
- Key metrics: DAU, total wagered, app conversion rates.
C. Livestreaming Events & Clinics
- Deploy in UK/US/Caribbean. Combine GPS overlays, drone footage, and wearable data.
- Key metrics: Viewership minutes, audience engagement, ROI from sponsorships.
D. Clinics & On-Demand Coaching
- Pilot in Ireland and California with hybrid video/live formats.
- Metrics: Rider retention, revenue/student, geographic expansion of content.
Caribbean Revival Strategy
Impact of COVID-19:
- Closure of Caymanas Park halted Jamaica’s core racing industry. Barbadian racing also stalled. USVI suspended all operations.
- Over 20,000 livelihoods affected indirectly; CTA (Thoroughbred Aftercare) overwhelmed with no transport/quarantine budget.
Recovery Initiatives:
- Barbados Gold Cup revived with Sandy Lane sponsorship.
- USVI introduced new safety rules and facility oversight in 2025.
- Jamaica reopened racing under revised protocols with Racing Commission oversight.
Investment Levers:
- Digitize OTB networks across islands.
- Fund CTA’s capacity with donor-backed welfare bonds.
- Introduce pilot digital passports for vaccinated, race-ready horses.
- Use livestreaming to connect diaspora communities and unlock ad revenue.
Strategic Roadmap
- Build financial models per region and vertical.
- Identify anchor partners for each pilot.
- Produce investment and pilot-ready decks.
- Apply for national/regional grants and stakeholder support.
Conclusion
The global horse racing and equestrian ecosystem is at a critical juncture—rooted in tradition yet ripe for reinvention. Elite events continue to deliver prestige and profitability, but sustainable growth lies in activating grassroots networks, digitizing core systems, and reaching new audiences through technology.
The Caribbean represents both a cautionary tale and an emerging opportunity—where modest investment in digital infrastructure, health tech, and content monetization could reestablish a vital regional industry. Through coordinated public–private partnerships, modern equestrian sport can expand beyond elite silos into a connected, inclusive, and globally scalable industry.
-
Boardroom Briefing: Cybersecurity as a Strategic Imperative
Introduction
Over the past few months we have had a lot of requests for Cyber Security briefings as the profile of attacks is becoming more widespread, and the scale of the attacks more damaging. This briefing summarises the global cyber security market and is intended to provide a business focused briefing to senior executives.
Part I: Global Cybersecurity Market Overview
Cybersecurity is no longer a backend IT concern. It is a top-tier boardroom priority, directly linked to business continuity, shareholder value, and brand trust. CEOs must now be fluent in the language of digital risk.
Market Dynamics:
- Global Market Size: US$245.6 billion in 2024, projected to reach over US$500 billion by 2030 (CAGR: 12.9%).
- Sector Growth: Cybersecurity is outpacing general IT spend. AI, cloud computing, and remote work are key accelerators.
- Cyber Insurance: Expected to grow from US$14 billion in 2023 to US$29 billion by 2027, highlighting growing risk awareness.
- Regional Trends:
- North America: Highest maturity in cyber defence but most targeted.
- Europe: Strengthening through GDPR and NIS2 Directive.
- Asia-Pacific: Rapid investment, especially in financial services and telecom.
Part II: Strategic Threat Landscape
The AI Arms Race
- 30,000+ new vulnerabilities disclosed in 2024 (up 17% YoY).
- Attackers are using AI to enhance phishing, malware, and social engineering.
- Defenders are responding with AI-powered threat detection and SecOps automation.
Cloud and Supply Chain Risk
- Cloud misconfigurations and third-party access now account for over 60% of breaches.
- Notable 2024 incidents: breaches involving Microsoft, Snowflake, and CrowdStrike.
Skills Shortage
- 470,000 cybersecurity job vacancies in the U.S. alone.
- Women expected to represent 30% of the cyber workforce by 2025, up from 25%.
Regulatory Pressure
- U.S. Executive Orders (e.g., EO 14028), GDPR, China’s Cybersecurity Law, and sector-specific mandates are raising the bar.
Part III: Real-World Examples
- SolarWinds (2020): Nation-state attackers exploited software updates, affecting thousands.
- Snowflake Breach (2024): Customer environments compromised due to lax identity access practices.
- Colonial Pipeline (2021): One leaked password caused fuel disruption across the U.S.
- Marks & Spencer (2024): £300 million loss following a cyberattack that crippled online sales and stole customer data.
Part IV: The CEO’s Role in Cybersecurity
The CEO doesn’t need to be a technologist, but must:
1. Frame Cybersecurity as Business Risk
- Understand cyber risks like financial or operational risks.
- Scenario plan for worst-case events: What happens if your data, payments, or services go offline?
2. Align Security with Strategy
- Cybersecurity should not block innovation. It must enable safe cloud adoption, AI deployment, and M&A integration.
3. Lead a Culture of Resilience
- Cyber awareness must be part of onboarding, executive training, and KPIs.
- Promote secure behavior at every level of the organisation.
4. Drive Investment with ROI in Mind
- Security investments should be framed in terms of risk reduction, regulatory compliance, and competitive advantage.
- Consider cyber insurance, tabletop exercises, red-teaming, and incident response planning.
5. Engage the Board and Stakeholders
- Translate technical risk into financial and reputational impact.
- Be transparent about breaches and response plans.
Part V: CEO-Level Strategic Agenda
- Integrate Cybersecurity into Core Business Planning
- Embed security reviews into digital initiatives and product development.
- Prioritise AI-Augmented Defence
- Leverage automation for detection and incident response.
- Review Cloud and Supply Chain Exposure
- Apply zero-trust principles, audit vendor practices.
- Tackle the Talent Gap
- Upskill internal teams, partner with managed services.
- Prepare for Regulatory Scrutiny
- Ensure documentation, logging, and breach notification readiness.
- Benchmark Against Industry Standards
- Use NIST, ISO 27001, and CIS controls as baseline tools.
- Test Your Defenses
- Regularly conduct simulations, stress tests, and external audits.
Closing Thoughts
The CEO must view cybersecurity as a strategic lever, not a sunk cost. With AI, cloud, and global threats converging, digital resilience is now a defining competitive advantage.
-
Should Founder CEOs Stay or Step Aside as a Business Grows?
Introduction
The startup journey is often synonymous with the founder CEO—the visionary who takes an idea from napkin sketch to product launch. But as the business scales, the role evolves from innovator to operator, demanding a different skill set. This raises a critical question: Can and should founder CEOs remain in their role as the business matures? The answer is nuanced and depends on the founder’s capabilities, the company’s trajectory, and its operational complexity.
The Founder CEO: Visionary or Operator?
Founders are typically driven by vision, passion, and adaptability—traits essential in the chaotic early stages of a startup. But scaling a business introduces new challenges: managing larger teams, navigating regulatory landscapes, and satisfying investor expectations. These responsibilities often require operational expertise, financial discipline, and process-oriented thinking—skills not all founders naturally possess.
Harvard Business Review found that by the time startups go public, only 50% of founder-CEOs are still at the helm. In venture-backed startups, that number drops to 25% by the third funding round (Noam Wasserman, The Founder’s Dilemma).
When to Reassess the Role
There are several indicators that it might be time for a founder to step back or change roles:
1. Scaling Complexity Outpaces Founder Skills
As companies hit the Series B/C stage, they require leaders with experience managing hundreds of employees, supply chains, and compliance regimes. If the founder lacks this experience—and doesn’t want to learn—it may be time to bring in a seasoned executive.
2. Investor or Board Pressure
Investors often push for leadership changes to de-risk their capital. This is especially true when growth stagnates or metrics fall short.
3. Burnout or Loss of Passion
The founder journey is grueling. If passion fades or health declines, stepping back may serve both the company and the founder’s well-being.
4. Transitioning to a Strategic Role
Many founders thrive in innovation, not in bureaucracy. Taking a role as Chief Innovation Officer, Chairperson, or Head of Product can preserve their influence without compromising operational efficiency.
Real-World Examples
Success in Transition
- Google: Larry Page stepped aside as CEO in 2001, handing the reins to Eric Schmidt, a seasoned executive who scaled the business. Page later returned when the company needed a fresh vision before eventually transitioning to Alphabet.
- LinkedIn: Reid Hoffman stepped down as CEO in 2007, handing leadership to Dan Nye, then Jeff Weiner. Hoffman stayed active as Executive Chairman, guiding strategic direction while professional management scaled operations.
- Netflix: Reed Hastings co-founded Netflix in 1997 and remained CEO until 2023, when he stepped into the Executive Chairman role, handing control to co-CEO Ted Sarandos and Greg Peters. The transition was well-received by markets and signaled maturity.
Staying Too Long
- WeWork: Adam Neumann’s leadership style became a liability as the company prepared to go public. His refusal to cede control and poor governance practices contributed to a failed IPO and loss of billions in valuation.
- Blackberry: Mike Lazaridis and Jim Balsillie co-led the company through its meteoric rise but failed to adapt to the smartphone era. Their resistance to change leadership contributed to a dramatic fall from dominance.
A Founder’s Options: Role Evolution, Not Exit
- CEO with Support: Bring in a strong COO or President to handle operations while retaining CEO title.
- Executive Chair or Founder Chair: Maintain influence over vision, governance, and culture.
- Product/Innovation Lead: Focus on what you love—building and innovating—without the admin burden.
- Board Member or Advisor: Take a long-term strategic seat and mentor the new leadership.
The Market’s View
Markets tend to reward maturity in leadership. A 2018 McKinsey report found that companies with experienced leadership teams outperformed others by 30% in revenue growth and 25% in profitability. Similarly, public investors often view leadership transitions as positive when founders are replaced by experienced operators—provided the transition is smooth and aligned with company vision.
Conclusion: Know When to Lead and When to Let Go
Being a founder CEO is an incredible achievement. Staying in the role should depend on whether the founder can adapt to the growing demands of the business. If not, it’s not a failure to step aside—it’s strategic maturity.
Ultimately, the best founder CEOs know when to reinvent themselves—and when to empower others to lead.
-
Why Most Startups Fail – And How You Can Turn the Tide
The world of startups is as intoxicating as it is unforgiving. For every unicorn that captures headlines and venture capital windfalls, hundreds quietly collapse in the shadows. It’s not for lack of ambition or effort—but often due to a repeatable pattern of missteps. Understanding why most startups fail is not only essential for entrepreneurs and investors alike, but also for those who see value in turning around distressed assets before they’re lost forever.
According to a 2024 report from CB Insights, nearly 65% of startups fail within their first ten years, with the most precarious time being years two through five. These aren’t random acts of misfortune—they’re the result of systemic weaknesses that can, in many cases, be mitigated or even reversed with the right strategy, leadership, and support.
In this expanded article, we explore the fundamental reasons why startups falter, highlight real-world examples of spectacular collapses, provide current market data, and examine the complex relationship between founders and investors. We also explore how strategic advisory firms like Kognise can play a pivotal role in turning around troubled ventures and unlocking long-term value from what many might prematurely consider a lost cause.
1. No Market Need – Building a Solution in Search of a Problem
42% of startups fail because they create products no one wants or needs.
— CB Insights, 2024The most common reason for failure is the most preventable: building something without validating whether anyone actually needs it. Founders often fall into the trap of becoming obsessed with their technology, idea, or vision, rather than the problem it solves or the customer who experiences that problem.
Take Quibi, for example—a mobile-first streaming service that raised an astonishing $1.75 billion from top-tier investors. It was marketed as the next evolution in content consumption. But within six months of launching in 2020, the platform shut down. The content wasn’t engaging enough to pull users away from YouTube, TikTok, or Netflix, and the format (10-minute episodes in portrait view) was a solution to a problem that simply didn’t exist.
Lesson: The best startup ideas come from validated pain points, not visionary guesswork.
2. Running Out of Cash – Burn, Baby, Burn (Until It’s Gone)
38% of startups fail because they run out of cash or can’t raise additional capital.
Cash is the oxygen of any business. Startups often make the mistake of treating funding rounds as finish lines rather than fuel stops. Overspending on growth without solid financial controls or a clear revenue model can accelerate death rather than scale success.
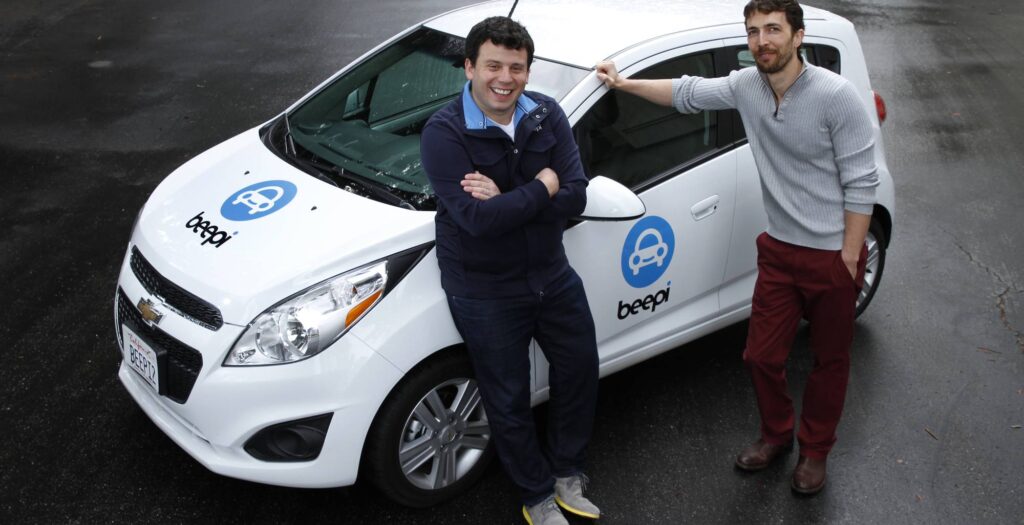
A prime example is Beepi, a Silicon Valley-based used car marketplace that raised over $150 million and achieved a paper valuation of more than $500 million. However, Beepi’s overhead costs, bloated payroll, and lack of operational discipline led to its demise in 2017. The company expanded too quickly and failed to match growth with sustainable revenue.
Lesson: Raising capital doesn’t mean you’re winning. Managing capital is where the real game begins.
3. Team Issues – Dysfunction, Ego, and Gaps in Execution
23% of failed startups cite team issues or leadership deficiencies as a core problem.
The founding team is the nucleus of any early-stage business. When that nucleus is unstable—whether due to skill gaps, misaligned vision, or toxic dynamics—the business unravels quickly. In fast-moving environments, the inability to make decisions, communicate honestly, or adapt constructively can be catastrophic.
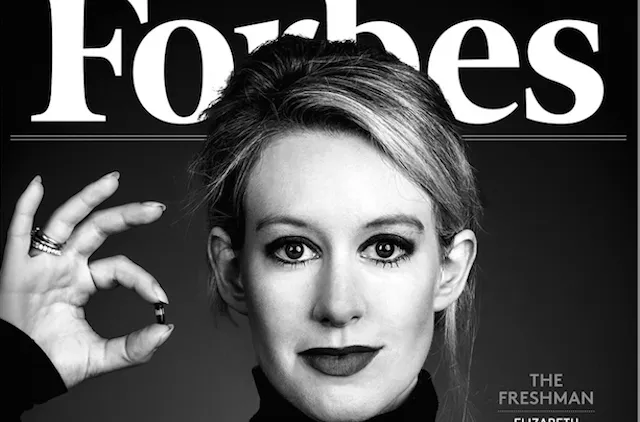
Theranos, perhaps the most infamous startup of the 2010s, serves as a warning. The company raised over $700 million in venture capital on the promise of revolutionizing blood testing. But the internal culture—guarded, siloed, and unquestioning of its founder’s vision—created a house of cards. A lack of experienced biotech oversight and the suppression of dissenting voices enabled massive fraud.
Lesson: A visionary founder isn’t enough. Execution requires diversity, discipline, and challenge.
4. Poor Investor Dynamics – When Capital Becomes a Liability
While most founders obsess over raising capital, few are prepared to manage it—especially when it comes with expectations that are misaligned with the business’s maturity or market timing. A toxic investor relationship can force a company to prioritise vanity growth metrics over long-term sustainability or force pivots that cannibalise momentum.
Consider WeWork. What began as a promising real estate-tech hybrid rapidly became a cautionary tale of overvaluation, corporate governance collapse, and unchecked ambition. Adam Neumann, the charismatic founder, was heavily backed by SoftBank, which infused billions in capital but failed to impose guardrails. The result? A $47 billion valuation imploded just before its IPO, resulting in massive layoffs and reputational damage.
Lesson: Investors are not just financiers; they are strategic partners. When that relationship fails, the business often follows.
5. Inability to Pivot – Refusing to Adjust the Course
Adaptability is a survival skill in startup life. Yet some founders cling to their original vision long after the market signals it’s no longer viable. When data suggests change, but ego or internal resistance prevails, failure is often just a matter of time.
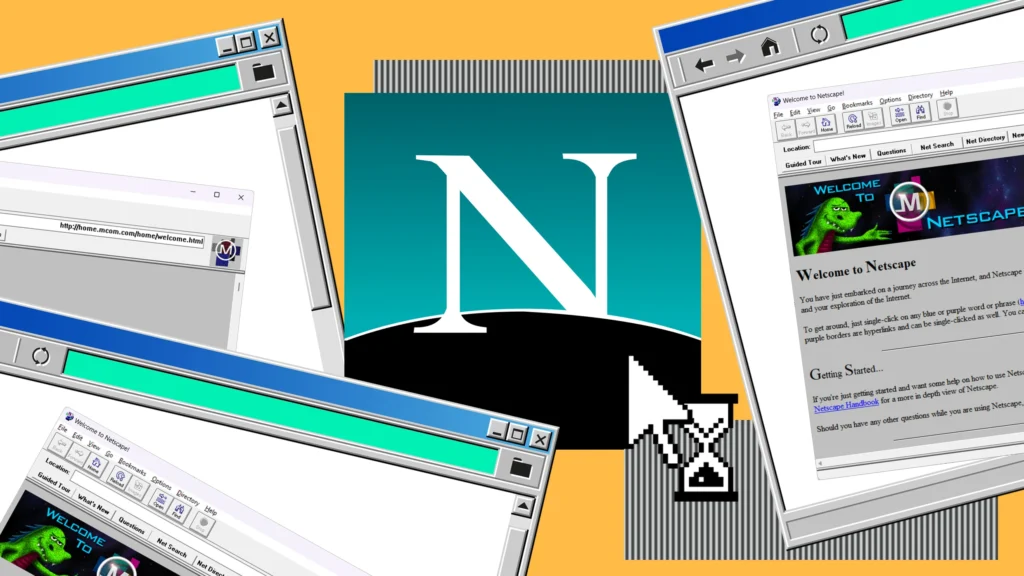
Netscape, once a dominant browser in the early internet era, failed to pivot fast enough in response to Microsoft’s aggressive entry into the space. Despite its first-mover advantage, Netscape didn’t innovate on the business model or product quickly enough and was eventually acquired by AOL in a much-diminished state.
Lesson: Startups don’t die from changing too much—they die from not changing fast enough.
Can Distressed Startups Be Saved?
Startup failure isn’t always final. Many so-called “distressed” ventures still have valuable intellectual property, market relationships, or growth potential—they’re just structurally unsound, financially imbalanced, or strategically misaligned.
This is where firms like Kognise enter the picture. A modern advisory outfit specialising in corporate revitalisation and venture strategy, Kognise helps unlock dormant potential in struggling startups.
How Kognise Adds Value to Distressed Startups
1. Governance Reform
Kognise performs full audits of leadership, board composition, and decision-making frameworks. A dysfunctional board or unchecked founder can tank value—restructuring governance brings back credibility and investor confidence.
2. Financial Triage and Restructuring
Whether the business needs bridge funding, cost restructuring, or financial modeling to support further rounds, Kognise offers deep financial expertise through fractional CFOs, funder-side negotiation support, and debt/equity rebalancing.
3. Investor Engagement and Repositioning
They reframe the company’s narrative to attract new capital or re-engage current investors. This includes pitch refinement, updated IMs, and repositioning strategies that reflect the actual value proposition and address investor concerns head-on.
4. Operational and Talent Gaps
Kognise connects startups with key interim talent—from NEDs and growth strategists to technical advisors—who can plug capability gaps without bloating fixed costs.
5. Market Repositioning and Exit Strategy
Some startups aren’t meant to scale but can still achieve profitable exits or pivots. Kognise evaluates asset value (IP, clients, tech stack) and can orchestrate M&A strategies that recover value.
Conclusion: Failure Isn’t Final—It’s a Signal
Startups fail, but not always for good reasons. Often, they just run out of the three things they needed most: time, support, and perspective. Strategic advisory can provide all three—giving founders a second chance and investors a chance at redemption or exit.
In a market where VCs are more cautious, LPs are more demanding, and capital is smarter, startups can no longer afford to guess, drift, or burn. They need partners, not just cheerleaders. They need process, not just passion. They need someone like Kognise, who can see the patterns, intervene early, and get things back on track.
-
Innovation Campuses: Unlocking Scalable Growth for Startups and Strategic Deal Flow for Investors
In the evolving landscape of entrepreneurship and technology, innovation campuses have become critical engines of growth, bringing together infrastructure, mentorship, capital, and collaboration under one strategic vision. These campuses are not just buildings; they are curated ecosystems designed to accelerate the success of startups and SMEs while offering investors consistent access to high-quality, investment-ready businesses.
Across the UK and beyond, a growing number of these innovation hubs are playing a transformative role in regional economic development and global innovation. Among them are Babraham Research Campus, Engine Shed, Harwell Science and Innovation Campus, Innovation Birmingham, Sci-Tech Daresbury, and Plexal—each offering a distinct value proposition for high-growth businesses and their backers.
Having worked directly with Plexal and its MD, Andrew Roughan, I’ve seen firsthand the power of a purpose-built innovation campus that blends cybersecurity, infrastructure, and government tech in the heart of London. Plexal’s ability to foster collaboration between high-potential startups and national government departments creates one of the most relevant and future-facing innovation platforms in the country.
More recently, having moved further north, I’ve had the opportunity to become more actively involved with Sci-Tech Daresbury, where the quality and ambition of its business community is equally compelling. I’ve worked alongside John Leake, Business Growth Director, and Paul Treloar, Head of Business Support—both of whom are dedicated to enabling meaningful outcomes for founders and investors alike. My close colleague and friend Richard Lydon has also been hugely active in this community, and his experience and insight have only deepened my appreciation for what this regional powerhouse is building.
Examples of Leading UK Innovation Campuses
Babraham Research Campus (Cambridge): A leader in life sciences innovation, Babraham offers cutting-edge lab facilities, commercialisation support, and access to the Cambridge biotech cluster. It has become a magnet for venture-backed health and biotech companies. Notably, Crescendo Biologics, a cancer therapeutics firm, scaled from concept to significant funding rounds on campus.
The Engine Shed (Bristol): A regional innovation hub linking academia, industry, and finance, Engine Shed is central to the West of England’s startup ecosystem. Its focus on inclusive growth and regional innovation attracts tech and creative companies alike. Successful alumni include Ultraleap, which began life in the Bristol ecosystem and now leads the world in mid-air haptics and gesture recognition.
Harwell Science and Innovation Campus (Oxfordshire): With a concentration of space, clean energy, and life sciences innovators, Harwell is one of the UK’s largest research-driven ecosystems. It benefits from deep public-private collaboration and a steady influx of institutional capital. Companies like OxSyBio, now part of 3D bioprinting pioneers FabRx, leveraged Harwell’s unique access to technical infrastructure and talent.
Innovation Birmingham Campus: A Midlands-based tech hub that supports digital companies with growth programmes, workspace, and university links. Operated by Bruntwood SciTech, it is part of a wider network of innovation-focused real estate assets. Whisk.com, which developed a smart food platform and was later acquired by Samsung, emerged from this ecosystem.
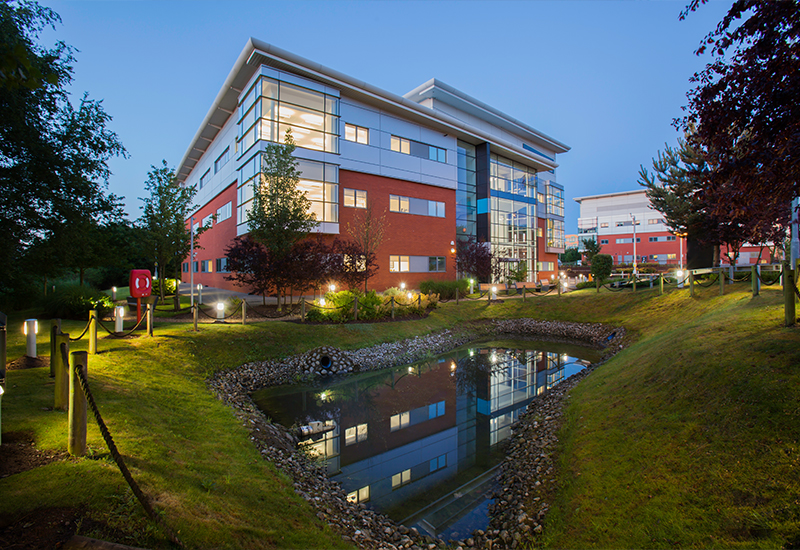
Sci-Tech Daresbury
Sci-Tech Daresbury (Cheshire): A science and technology campus supporting companies across sectors like engineering, health tech, and clean energy. It provides access to STFC’s Daresbury Laboratory, business support programmes, and links to regional and national investor networks. Notable alumni include Perfectus Biomed, a microbiological testing firm now working internationally, and ORCHA Health, which has become a global leader in digital health app evaluation.

Andrew Roughan (MD Plexal)
Plexal (London): Based at Here East in London, Plexal supports startups in cybersecurity, mobility, and digital infrastructure. It offers accelerators, public sector pilot opportunities, and access to national security and government innovation networks. Successful residents include TrueCircle, an AI startup tackling the circular economy, and Synalogik, a data fusion platform working with law enforcement and regulators.
Each of these campuses demonstrates how place-based innovation strategies can unlock local economic growth while plugging startups into global investment and talent pipelines.
The Ecosystem Advantage: Why Innovation Campuses Work
The value of these environments goes beyond office space:
- Integrated support: Startups can access commercialisation experts, legal and IP advisors, grant writers, and financial modelling experts all within the campus.
- Network density: Co-location with other innovators, researchers, and funders fosters peer learning and serendipitous partnerships.
- Credibility uplift: Being part of a recognised innovation campus lends validation in the eyes of investors and grant providers.
- Access to talent: Many campuses partner with universities or run embedded placement programmes that connect businesses to highly-skilled graduates and researchers.
- Investor matchmaking: From demo days to strategic introductions, campuses act as filters for high-quality deal flow, reducing friction for both founders and investors.
These benefits also make a difference to policy. Innovation campuses are increasingly recognised by government as ideal channels for distributing grant funding, piloting new technologies, and accelerating strategic national priorities—from decarbonisation to digital infrastructure.
The Investor Perspective: Scouting with Confidence
For early-stage investors, innovation campuses provide:
- Pre-vetted deal flow with strong commercial and technical foundations
- Ongoing visibility into company progression and pivots
- Lower due diligence costs due to transparency and structured support
- Opportunities to co-invest with public sector and institutional capital
This alignment between investor needs and founder growth unlocks efficiencies and reduces friction in early-stage capital markets. Investors are increasingly embedding themselves into these ecosystems to stay ahead of market trends and source deals earlier.
Looking Ahead
The innovation campus model is expanding globally, with countries replicating successful templates like those found across the UK. As governments, universities, and private investors coalesce around place-based innovation, these campuses will be the epicentres of economic transformation.
For founders, the message is clear: don’t go it alone. For investors, it’s a reminder that some of the most exciting opportunities are growing not just in boardrooms or pitch decks, but in the curated environments where innovation is built daily.
Innovation campuses are more than hubs—they are launchpads.
-
Market Update for Sustainable Startups and Biodiversity Net Gain (BNG) Providers: Investment Outlook and Five-Year Forecast
As global priorities shift toward environmental resilience and net zero ambitions, sustainable startups and biodiversity-focused enterprises are experiencing a surge in relevance. Within this ecosystem, Biodiversity Net Gain (BNG) providers are emerging as strategic actors aligned with both regulatory mandates and market opportunity. This article explores the current status, investor outlook, and five-year trajectory for these businesses, backed by real-world examples and market data.
The Current Market Landscape
The global market for sustainable startups is growing at unprecedented rates. According to PwC’s 2023 State of Climate Tech report, climate tech startups raised more than $60 billion in 2023 alone. Of this, approximately $4.7 billion was directed toward nature-based solutions, including biodiversity monitoring, regenerative agriculture, and habitat banking. This represents a fourfold increase from 2020, indicating the speed with which investor sentiment is turning toward natural capital.
In the UK, the implementation of the Environment Act 2021 mandates that all developments must deliver a minimum of 10% biodiversity net gain. This is expected to generate a market demand for more than 6,000 biodiversity units per year, with prices ranging from £12,000 to over £30,000 per unit, depending on habitat type and location. This gives a conservative estimated market value of £150M to £500M annually, with some forecasts suggesting this could grow to £2 billion by 2030.
Example: Environment Bank, one of the UK’s leading BNG providers, secured a £240 million investment in 2022 from Gresham House to develop over 100 habitat banks. These will generate thousands of units, underpinning compliance for housebuilders, infrastructure developers, and planning authorities.
BNG startups now include operators such as CreditNature, Greenspace Ecological Solutions, and Legacy Habitat Banks Ltd, offering services from land restoration to biodiversity unit sales and data reporting. Increasingly, startups are integrating satellite monitoring (e.g., via Planet Labs) and AI-based habitat classification to offer a seamless investor- and regulator-friendly experience.
Investor Sentiment: Seed to Private Equity
Seed and Angel Investors: The early-stage ecosystem is increasingly mission-aligned. According to Angel Investment Network UK, cleantech and nature-based solution deals made up nearly 18% of total deal volume in 2023, up from just 6% in 2019. Notably, seed investors are drawn to first-mover advantage and the relatively low upfront capital required to establish initial habitat sites.
Venture Capital: Firms like AENU, Pale Blue Dot, and Breakthrough Energy Ventures have started explicitly referencing biodiversity and ecosystem impact as part of their investment thesis. These investors seek out platform-driven BNG businesses—those that can scale biodiversity tracking, trade habitat units digitally, and create software-based regulatory compliance tools.
Example: Downforce Technologies, an Australian-UK startup, raised $6 million in 2022 to scale its soil carbon and biodiversity analytics platform. It works with major landowners and has applications for BNG readiness assessments.
Family Offices: Private wealth managers are increasingly allocating a portion of their portfolio to regenerative land use and biodiversity restoration. A recent UBS survey indicated that over 60% of family offices intend to increase their exposure to sustainable land and climate-resilient agriculture. Offices such as the Grantham Foundation and Blue Earth Capital are backing initiatives that align biodiversity restoration with long-term capital preservation.
Private Equity: While still early-stage, PE firms such as TPG Rise and EQT Future are beginning to evaluate later-stage biodiversity opportunities—especially those with embedded recurring revenue (e.g., biodiversity unit trading or habitat monitoring-as-a-service).
Lenders and Impact Funds: Institutions like Triodos Bank, Innovate UK Loans, and the Green Investment Group are already deploying funding into nature-based projects. Blended finance structures are also being used—combining grant, debt, and equity to reduce the risk exposure for commercial capital.
Market Size and Economic Opportunity
Globally, the nature-based solutions market is expected to exceed $150 billion by 2030 (UNEP), with estimates suggesting that to meet climate and biodiversity targets, at least $384 billion annually will be needed (Nature Conservancy, 2022).
In the UK, the demand for biodiversity units is forecast to rise exponentially:
- 6,000–10,000+ units/year by 2025
- £1.5B+ market cap by 2027
- 12,000+ development sites expected to fall under BNG mandates
Additional economic drivers include:
- 30-year maintenance periods that make these services long-term and stable
- Voluntary biodiversity offset markets beginning to emerge alongside compliance-led BNG
- Carbon-Biodiversity hybrid credit models, where a single land project can sell both carbon and biodiversity units (e.g., peatland restoration or woodland creation projects)
Five-Year Outlook
- Institutionalisation & Regulatory Clarity: Biodiversity units will become more commoditised, tracked via registries (e.g., Natural England’s BNG register), and audited through remote sensing. Much like carbon markets, BNG trading platforms will emerge to facilitate transparency and liquidity.
- Consolidation & M&A Activity: Major infrastructure groups (e.g., Balfour Beatty, WSP) and real estate developers may begin acquiring BNG operators to internalise compliance and de-risk projects. Expect VC-backed startups to be acquired within 5–7 years for integration into larger ESG portfolios.
- Technological Evolution: AI, LIDAR, drone imagery, and real-time data platforms will allow BNG providers to prove impact at scale. Remote compliance verification will reduce costs and attract institutional investors.
- International Replication: Following the UK’s model, Australia, parts of the EU, and even the U.S. (under state-level climate mandates) are considering BNG-style regulations. The OECD is actively evaluating market-based biodiversity frameworks.
- Investor Maturity: Impact investors and ESG-focused institutions will demand better metrics, risk-adjusted returns, and clear exit pathways. BNG projects with embedded land rights, long-term management plans, and digital audit trails will command valuation premiums.
- Exit Pathways: Exits will likely include:
- Acquisitions by infrastructure, planning, or housebuilding consultancies
- Integration into nature investment funds or REIT-like vehicles
- Buybacks and secondary sales at 6–12x EBITDA or 5–10x revenue multiples for high-performing ventures
Conclusion
Sustainable startups—and BNG providers in particular—are no longer fringe participants in the impact economy. They are gaining mainstream visibility and capital access, thanks to regulatory mandates, rising investor interest, and maturing technology platforms.
With the UK market at the forefront of global biodiversity monetisation, and real examples like Environment Bank’s £240M raise or Downforce’s soil platform scaling internationally, the next five years are poised for consolidation, innovation, and rapid growth.
For founders, this is a rare moment to shape a market before it becomes saturated. For investors, it’s a chance to back scalable, mission-aligned businesses with measurable impact and strong returns.
Nature, long undervalued, is becoming a recognised asset. The businesses that harness this shift—credibly, transparently, and at scale—stand to lead not only the next wave of green innovation but the redefinition of value itself.
-
From Steady to Scaling: Why Post-Investment Businesses Need Strategic Support to Thrive
There’s a saying in business that rings especially true once the early-stage adrenaline wears off:
“You either thrive, survive—or nose-dive.”Many companies that have achieved steady turnover or secured initial investment find themselves stuck in a dangerous middle ground—not failing, but not growing either. Ironically, a business that’s stable but stagnant can be riskier than one in active growth mode.
Here’s why—and how advisory firms like Kognise help unlock structure, momentum, and strategic clarity to scale.
Market Snapshot: The Mid-Market Growth Plateau
According to a Harvard Business Review study, nearly 80% of companies that reach the £2M–£10M turnover range never scale beyond it.
Further data from McKinsey & Company shows:
- Only 22% of mid-sized firms maintain consistent year-on-year growth over a 5-year period
- Companies that stall for 2+ consecutive years have a 68% higher risk of decline or failure
- Operational drag and misaligned capital allocation are among the top reasons for post-investment underperformance
The Myth of “Steady Is Safe”
It’s tempting to think that hitting £3–5M in turnover and posting consistent margins is a win. And to a degree, it is. But “steady” can breed complacency.
- Teams lose urgency
- Talent gets stale
- The founder spreads too thin
- Systems stay manual
- Capital sits underutilized—or misused
Your business becomes a sleeping giant—or a shrinking one.
Steady businesses often carry hidden risk—because they’ve stopped evolving.
Case Examples: Thrive, Survive, and Nose-Dive
THRIVE: Gymshark
Birmingham-based Gymshark started as a side hustle and scaled rapidly after reaching consistent 7-figure revenue. Instead of plateauing, they:
- Brought in a professional CEO
- Invested in international expansion
- Streamlined operations and brand positioning
By 2020, they achieved £260M+ turnover and received investment from General Atlantic—valuing the business at over £1B.
Lesson: Even a profitable business can grow exponentially with the right strategic shifts.
SURVIVE: Made.com
Made.com was once Europe’s fastest-growing online furniture brand, hitting £315M in revenue. But after its IPO, growth plateaued and:
- Operations became inefficient
- Cash burn increased
- Leadership struggled to pivot during supply chain disruptions
In 2022, the business collapsed into administration.
Lesson: A steady top line means little if operations, leadership, and adaptability aren’t built for scale.
NOSE-DIVE: Theranos
Theranos was once valued at $9B, but cracks appeared after early product hype turned into operational stagnation and regulatory scrutiny. Despite seemingly steady progress:
- KPIs were misleading
- Internal accountability was weak
- Capital raised wasn’t matched by credible delivery
The company dissolved in disgrace in 2018, and its founder was later convicted of fraud.
Lesson: A company that appears stable—or even impressive—can quickly collapse if growth is not real, grounded, and well-managed.
How Kognise Helps Businesses Grow With Confidence
At Kognise, we work with businesses that are past survival but not yet built to scale. We help you transition from founder-led to system-led, with a clear path to growth.
Here’s how we help:
1. Strategic Clarity
We help define and pressure-test:
- Scalable positioning and product lines
- Growth levers and go-to-market strategies
- Execution roadmaps for 12–18 months
2. Operational Infrastructure
We support teams in:
- Redesigning org charts and functional accountability
- Embedding reporting cadence and internal governance
- Setting KPIs and dashboards for performance tracking
“Structure is not bureaucracy—it’s what enables speed at scale.”
3. Financial Control & Capital Allocation
We help founders:
- Model multiple growth scenarios
- Plan for headcount and margin protection
- Work with fractional CFOs and finance teams to protect runway
CB Insights lists “ran out of cash” as the #2 reason startups fail—we help ensure it doesn’t happen to you.
4. Investor & Board Engagement
Whether you’re reporting to a VC, private equity firm, or family office, we ensure:
- Board decks are clear and actionable
- Investor confidence is maintained
- The business is ready for next-round funding or acquisition
Thrive, Survive, or Nose-Dive
Let’s return to that framework:
Stage Description Thrive Structured, scalable, and built to grow with professionalised systems and leadership Survive Treading water, often overstaffed, understructured, and vulnerable to market shifts Nose-Dive Loss of momentum, investor fatigue, talent exodus, or catastrophic operational issues Final Thoughts: Risk Isn’t Just for Startups
If your business has been steady but flat, the question is not “what are we doing wrong?”
It’s “what are we failing to evolve?”Kognise supports businesses in this critical mid-phase—ensuring founders have the tools, guidance, and structure to turn a steady business into a scalable one.
If you’re sitting on a plateau—or about to—let’s talk about how we can help you thrive, not just survive.
-
Investor Pitch Sessions: What to Expect & How to Win
Pitching to investors is one of the most pivotal moments for any founder. Whether it’s your first meeting or a follow-up, your goal is to build confidence, show clarity, and spark conviction. The format might be a face to face session but the initial meeting these days may also be a video call.
Here’s how to get it right—with tools, examples, and prep strategy.
Pitch Meeting Checklist: What to Bring & Cover
Item Purpose Concise pitch deck (10–12 slides) Clear, story-driven overview of your business Financial model (high-level) Top-line P&L, assumptions, runway needs Cap table Current ownership, past rounds Fundraising ask How much, use of funds, terms (if available) Key metrics CAC, LTV, MRR/ARR, churn, MoM growth, burn Prepared Q&A notes Anticipate objections and pressure points Calendar availability For follow-ups or partner meetings Sample Investor Questions with Model Answers
“What problem are you solving?”
Model Answer:
“We’re solving the inefficiency in SME logistics by automating back-office operations, saving businesses up to 40% in admin time. It’s a pain point we validated through 50+ user interviews and beta pilots.”“How big is the market?”
Model Answer:
“Our initial TAM is £3.2B in the UK logistics tech market. But the broader opportunity across the EU and North America is closer to £25B. We’re focused on a niche wedge that can expand rapidly.”“What traction do you have?”
Model Answer:
“We’ve grown revenue 40% month-over-month for the last 5 months, with 1,200 active users and a 91% retention rate. We’ve just signed a partnership with [X] and expect to double volume in Q3.”“What’s your business model?”
Model Answer:
“We operate a subscription model with usage-based pricing layered in. Our ARPU is £52/month today, and we expect to grow that through value-added features and integrations.”“Why your team?”
Model Answer:
“Our team blends domain expertise and execution. I previously led ops at a logistics firm that scaled to 8 figures, and our CTO built enterprise-grade systems at [relevant company].”“How will you use the funds?”
Model Answer:
“We’re raising £1.2M to expand engineering, strengthen go-to-market, and extend runway to 18 months. The goal is to hit £1M ARR and reach Series A readiness.”How to Prepare for a Pitch (and Why Kognise Can Help)
Investor meetings are not won in the room—they’re won in preparation.
1. Run Mock Pitches
Use founder coaches, advisors, or firms like Kognise to simulate investor meetings. We help:
- Stress-test your messaging
- Pressure-test your numbers
- Identify red flags and refine narrative
2. Know Your Audience
Every investor is different. We help you:
- Research their portfolio and investment thesis
- Tailor your messaging to align with their interests
- Position your raise in a way that resonates
3. Prepare a Leave-Behind Pack
Have a clean post-meeting pack ready:
- Pitch deck PDF
- One-pager or investment memo
- Summary financials
4. Be Clear on the Ask
We work with founders to articulate:
- Exact funding amount and use of funds
- Deal structure (SAFE, equity, convertible note)
- Target outcome (next round or profitability milestone)
How Kognise Supports Founders
At Kognise, we work alongside ambitious founders to prepare investor-ready materials and open doors to capital. Our pitch prep services include:
- Pitch deck refinement and investor storytelling
- Mock VC meetings with real-time feedback
- Financial model review and unit economics breakdown
- Targeted outreach strategies to family offices and institutional capital
We bridge the gap between a great idea—and a funded, investable business.
Final Thoughts
Pitch meetings aren’t easy—but they become a lot easier with the right preparation, positioning, and partner.
If you’re preparing to raise capital, now is the time to invest in the clarity and confidence that will define your success in the room.
Need help preparing? Let’s talk.
-
Understanding Family Offices
Family offices have become one of the most important—and misunderstood—capital allocators in the private markets today. From backing startups to acquiring real estate and managing intergenerational wealth, family offices are increasingly active across investment landscapes.
But what are they, how many exist, and how can entrepreneurs or fund managers effectively engage with them?
How Many Family Offices Are There Globally?
Estimates vary due to the private nature of family offices, but as of 2024, the landscape looks like this:
- Single Family Offices (SFOs): ~12,000 worldwide
- Multi-Family Offices (MFOs): ~4,000 firms serving thousands of families
- Total capital under management: $10–15 trillion globally
Geographic distribution:
- 🇺🇸 North America: ~50% of all family offices
- 🇪🇺 Europe: ~30% (strong hubs in Switzerland, UK, Germany)
- 🌏 Asia & Middle East: Rapid growth, especially in Singapore, Dubai, and Hong Kong
- 🇦🇺 Australia & LATAM: Growing presence among UHNW individuals
How Are Family Offices Categorised?
1. By Structure
Type Description Single Family Office (SFO) Manages wealth for one family; fully bespoke and private Multi-Family Office (MFO) Serves multiple families; offers shared resources and economies of scale Virtual Family Office Lean, tech-enabled setup, often with outsourced services and minimal overhead 2. By Investment Philosophy
Category Focus Preservation-First Low-risk, long-term wealth management, with conservative allocation Opportunistic Active investors in venture, PE, real estate, alternatives Mission-Driven Focused on impact investing, ESG, philanthropy Entrepreneur-Led Backing founders and ventures that align with their industry expertise How Do Family Offices Operate?
Family offices typically manage the financial, administrative, and sometimes personal affairs of ultra-high-net-worth families. Their structure varies, but core services often include:
- Investment Management – Portfolio construction, direct deals, fund allocations
- Wealth Planning – Tax structuring, estate planning, intergenerational transfers
- Operations – Bill pay, legal, HR, family governance
- Philanthropy – Managing foundations, impact investments, donations
- Lifestyle Services – Real estate, travel, education, private security
They can invest across public markets, private equity, venture capital, real assets, and even collectibles like art or wine.
How Kognise Works With Family Offices
Kognise has trusted relationships with many family offices across the UK, Europe, and the Gulf. We work closely with family principals, CIOs, and investment managers to:
- Source and evaluate investment opportunities
- Guide capital deployment strategies, especially across venture, growth, and alternative asset classes
- Align portfolio investments with family mandates—whether that’s growth equity, impact, or legacy ventures
On the flip side, Kognise also supports founders—helping startups craft tailored outreach, navigate due diligence, and secure aligned capital from private wealth sources.
This dual-sided expertise allows Kognise to bridge the gap between exceptional entrepreneurs and long-term capital holders, creating value for both sides.
How to Select the Right Family Office to Approach
Not all family offices are open to outside pitches—and each has unique preferences. Here’s how to identify the right fit:
Match Their Mandate
- Study their sector focus (e.g., real estate, healthtech, AI, climate)
- Understand their stage preference (seed, growth, buyout)
- Align with their geographic focus and values
Look for Founder Alignment
- Many SFOs are built around a founder with an operating background.
If your business reflects their past industry, that’s a strong common ground.
Study Their Track Record
- Look for deals they’ve led or co-invested in
- Many participate quietly alongside VCs or PE firms—check Crunchbase, PitchBook, or deal news
Use Warm Introductions
- Direct outreach often fails. Instead:
- Go via their advisors (lawyers, accountants, private banks and Kognise)
- Connect at family office events or closed investor forums
- Ask mutual LPs or fund managers for intros
How to Engage a Family Office
- Be Specific
Tailor your pitch to their mandate—don’t send mass decks. - Build Trust Over Time
Relationship-first. Many don’t invest on first meetings and prefer to watch your progress over time. - Offer Co-Investment or Access
If they’re capital allocators into funds, offer access or sidecar opportunities. - Demonstrate Alignment
If you share a mission or family value (education, sustainability, legacy), make it personal. - Be Transparent
Family offices value long-term relationships. Honesty and clarity around risk, timeline, and exit matter more than hype.
Final Thoughts
Family offices are growing in influence and sophistication. For founders, fund managers, and dealmakers, they offer a patient, strategic capital source—but one that requires care, relevance, and long-term relationship-building.
Kognise is proud to act as a trusted partner to both sides of the table—supporting family offices in their investment journeys, and helping visionary founders secure capital that aligns with their mission and values.
In a world awash with transactional VC capital, the right family office can be your anchor investor, champion, and long-term partner—if you take the time to understand and earn their trust.