-
We Pivoted…
I had a fairly chilled-out weekend for once. I spent some time at an arts festival, which gave me a bit of space to reflect on how much Kognise has changed over the past year and where we’re taking it through the remainder of 2026 and into 2027.
We spend a lot of time advising businesses to recognise when their market has changed and be prepared to adapt. Looking back, that’s exactly what we’ve done ourselves. Kognise started primarily as an advisory business, working with founders around strategy, investor readiness, governance, growth, funding and ultimately exit. We still do all of that, but over the last year we’ve seen a common pattern of requirements emerging from both founders and funders, and we’ve adapted the business around them.
In other words, we’ve taken some of our own advice and pivoted.
The most visible change is the name. Kognise has become Kognise Capital. That doesn’t mean we’ve become a fund. Not yet, anyway. We’ve already had approaches from potential partners interested in exploring that with us and it’s certainly something we’re considering. It won’t happen this year, but it’s a direction we may look at as the business develops.
For now, Capital better reflects where much of our work is heading. We’re not just advising a company about a funding transaction. We’re helping it get into the right position to procure capital and increasingly looking at how that company will be funded over the next three, five or more years.
One of the parts I particularly enjoy is sitting down with a founder and working through the business. We normally start with a qualification call on Teams, but after that we want to meet people face-to-face and, where possible, meet the wider team. There are plenty of people offering lists of hundreds or thousands of funders and contact details. That’s not really what we do. Before we introduce a business to anybody, we want to understand the business and the people we’re putting in front of them.
We particularly want to see the team together. They’re going to have to take the business through the next few years, and some of those years will be difficult. Sitting around a table over a pile of coffee tells us things we simply don’t get from a deck or a Teams call. How do they work together? Who really knows the numbers? How do they challenge each other? Does the management team actually operate as a team?
AI doesn’t replace that. We use AI extensively and it can do an excellent job of analysing a model, reviewing a deck or challenging assumptions. It can’t sit around that table and get a feel for the people. There also needs to be some chemistry between us and the team. If we’re going to spend months working together through a difficult funding process, that matters.
There’s another conversation I seem to have with founders all the time, and it’s one where I regularly see the penny drop. They’ve built a sales deck and then taken it to a funder.
A good sales deck tells a customer why they should buy your product or service. The funder is looking at something different. If I’m putting £1m into your company, I want to understand how you’re going to turn my £1m into £3m, £4m or £5m. Obviously the product, market and people matter, but the funder is investing to make a return. They need to understand how the business grows in value, how much capital it will take to get there and how they eventually get their money out.
When we work through that with a founder, the conversation normally changes quite quickly. We stop just talking about why the product is good and start talking about why the business is a good investment.
I see something similar with new ideas. Someone develops a clever product and then starts looking for places to use it. I prefer to start with the market. What’s happening in it? What’s changed? What isn’t working particularly well? What do customers want that they aren’t getting? Is there a big enough opportunity to build a business around solving that?
I think that’s particularly relevant at the moment. We’ve had a succession of major disruptions to markets. COVID changed customer behaviour and operating models almost overnight. Supply chains were disrupted. Inflation and interest rates followed. More recently, geopolitical conflict has put further pressure on energy costs. For sectors such as hospitality, where energy, food, labour and property costs are difficult to remove, these shocks can fundamentally change the economics of established businesses.
That’s clearly difficult for the businesses caught in it, but from a startup and investment perspective there is another side to it. In a stable market, a new business may be trying to compete with incumbents that have scale, purchasing power, established customers, mature systems and a cost base optimised over decades. That’s a very difficult place from which to start.
Disrupt the market and some of those advantages change. Customer behaviour moves, established operating models become expensive and legacy systems and property can become constraints rather than advantages. A new entrant isn’t necessarily trying to beat the incumbent at its own game anymore. It has an opportunity to ask whether the game itself has changed.
We’ve seen throughout business history that periods of major economic, technological and social change create opportunities for new businesses and new models to emerge. I wouldn’t suggest that every major company was created in a recession, because that simply isn’t true, but there are plenty of examples of businesses that were created, transformed or accelerated when established markets were being disrupted. I think we’re in another of those periods now.
Hospitality is a good example for me personally. I used to be a Hilton Diamond member. I booked Hilton almost automatically, generally received good service and valued the benefits. What increasingly frustrated me was finding that the same Hilton room could sometimes be cheaper through Booking.com when the hotel was trying to fill capacity. I never really understood why my loyalty wasn’t better protected.
COVID eventually broke that habit. I don’t have the same loyalty to a hotel group anymore and the nearest thing I probably have now is Booking.com. That’s only my experience, but it’s exactly the sort of change we’d want somebody building a new hospitality business to investigate. How has customer behaviour changed? What do people value now? What frustrates them about the current experience? What costs are established operators carrying that a new model might avoid? If you started with a blank sheet of paper today, would you build the same hotel business?
I’ve seen some interesting hospitality businesses in the Netherlands taking quite different approaches, and that’s where I think the opportunity in disrupted markets sits. You don’t necessarily have to compete with established businesses on their terms. You can look at what’s changed and build something around the market as it is now.
The difficulty is that genuinely disruptive businesses can be harder to fund. Funders understandably like comparables because they make risk and value easier to assess. If you’re doing something genuinely different, there may not be five similar businesses to benchmark against. The founder therefore has to work harder to demonstrate that the market exists, customers actually want the change and the economics work.
Being different isn’t enough. The business still has to demonstrate how that difference creates value.
This is one of the reasons our investor-readiness work has changed. We don’t want to start with a list of funders. We want to start by asking whether the business is ready to talk to them. Does the model work? Is the market opportunity properly evidenced? How much capital is actually required? What does that money achieve? What happens if the plan is six months late? What happens when this money runs out? Most importantly, where does the funder’s return come from?
Sometimes we’ll tell a business that it isn’t ready yet. We’d rather do that than put a weak proposition in front of a funder and damage the opportunity.
We also continue to work on a non-exclusive basis. A client can talk directly to funders, use another adviser, use its own contacts or ask us to make introductions. We don’t need to control the route to the money. If we’ve helped get the business properly prepared and it secures the right capital, we’ve done our job.
Another thing that’s changed quite significantly is the way we look at the funding requirement itself. If a company needs £3m today but its plan says it will need another £10m over the following three years, I don’t think it makes sense to treat those as separate exercises. The decisions made in the first round can make the second round easier or considerably more difficult.
The numbers put some context around that. Dealroom data suggests around 29% of new UK startups secure funding and only around 27% progress from Seed to Series A. Getting the first round doesn’t mean you’ll get the second.
That’s why we’re now spending much more time looking at the Capital Journey™. If there are likely to be rounds one, two, three and four, let’s understand them now. What does each round need to achieve? How much capital is required and when? Does it all need to be equity? Could lending, asset finance, bonds or another structure make more sense at different points?
Funders are looking at this as well. One of the concerns we’ve heard is very simple: if I invest now, when I eventually want to exit, is there enough left in the business for the next investor to make a good return? Round one should increase the value of the business and make round two attractive. Round two needs to do the same for round three. A future investor still needs to see enough opportunity ahead to justify investing at a higher valuation.
Dilution is closely connected to this. We’ve seen founders give away too much equity early because they need to get a deal done, and then had a later funder question whether the founding team still owns enough of the company. It sounds odd at first, but the investor also needs the founders and management team to remain motivated to create the future value of the business.
This is why we think dilution has to be considered over the whole journey. What happens to the founders after round one? What happens after rounds two and three? Could we use another type of capital at one stage? Could we reach a milestone before raising more equity and get a better valuation? It’s not about avoiding dilution. It’s about getting the funding and dilution right for each stage without creating a problem further down the road.
We’ve made another change because of something we’ve repeatedly seen in projects. Funding and restructuring create a lot of work. There are models, forecasts, investor materials, due diligence, data rooms, lawyers, accountants, technical questions, funders and a constant stream of actions that somebody has to manage. A large corporate normally has project and programme people to do that. A startup or scale-up generally doesn’t, so the founder ends up managing the funding project while also trying to run the company.
That’s why we’ve developed the Kognise Delivery Office (KDO). We coordinate the parties, manage the actions and dependencies and keep the process moving. It’s not particularly complicated as a concept, but it solves a problem we’ve seen repeatedly. It keeps the founder focused on the business, helps control professional costs and gives the funder a better organised process. It also gives us the structure to manage more engagements properly.
We’ve also changed the way we think about exit. I increasingly ask founders a fairly simple question: what are you actually trying to achieve personally?
For many founders, the company will be the largest asset they ever create. What’s your number? What does financial independence look like? What do you want to provide for your family? If we’re modelling several rounds of funding and dilution, we should also understand what that ultimately means for the people who created the business.
That’s why we’ve partnered with Family Legacy. We’re not wealth advisers and we’re not trying to become wealth advisers. We simply want the founder’s personal financial journey to be considered alongside the company’s capital journey, with specialists involved where they’re needed.
We’re doing something similar around cyber security. It’s increasingly something funders ask about, but we don’t think the answer is automatically another certificate or a security model designed for a company ten times the size. We’re working with a specialist cyber business on what sensible cyber maturity looks like for a startup or scale-up at different stages of its development: what it actually needs now, what it should be planning for and what a funder should reasonably expect to see.
As we bring more specialist capability around Kognise Capital, we also need to make sure we don’t compromise our independence. We don’t want to find a cyber problem because we happen to have a cyber partner, or recommend personal financial planning because we have a relationship with Family Legacy. Sometimes our partner will be right, sometimes somebody else will be better and sometimes the client won’t need anything.
Looking back over the last year, we’ve done what we advise our clients to do. We’ve looked at what’s happening in our market, listened to the founders and funders we’re working with and changed the business around what we’re actually seeing.
Kognise Capital is therefore quite different from Kognise a year ago. We’re still advisers, but we’re doing much more around capital strategy and procurement. We’re looking at funding as a journey rather than a transaction. We’ve built KDO because our clients need help managing that journey, and we’re bringing specialist capability around it where we see genuine gaps.
And we may ultimately become a fund. We’re not there today, but it’s now a discussion we’re having.
There’s quite a lot more we want to do with Kognise Capital over the next twelve months, and some of it is already starting to take shape. It took a quiet weekend at an arts festival to realise quite how much we’d already changed.
We’ve pivoted.
-
Kognise becomes Kognise Capital
We’ve evolved Kognise into Kognise Capital, reflecting the business we are today and the way we now work with clients and capital partners.
We now work closely with a broad range of capital partners, spanning HNW and private investors, seed and venture funds, specialist lenders, asset finance providers and the bond markets. This gives us the ability to look across different forms of capital and structure the right approach for each business.
Importantly, we don’t see capital as a series of isolated transactions. We increasingly work with businesses on a multi-year capital journey, mapping the funding they will need as they grow, the right capital partners at each stage and how each funding point supports the next.
That can mean supporting a single transaction or working alongside a business across multiple funding points, bringing in different capital partners as its requirements develop.
The move to Kognise Capital reflects this broader role and our closer alignment with the capital partners we work with. We’ve rebranded and updated the website accordingly, bringing strategy, growth and capital together under one identity.
-
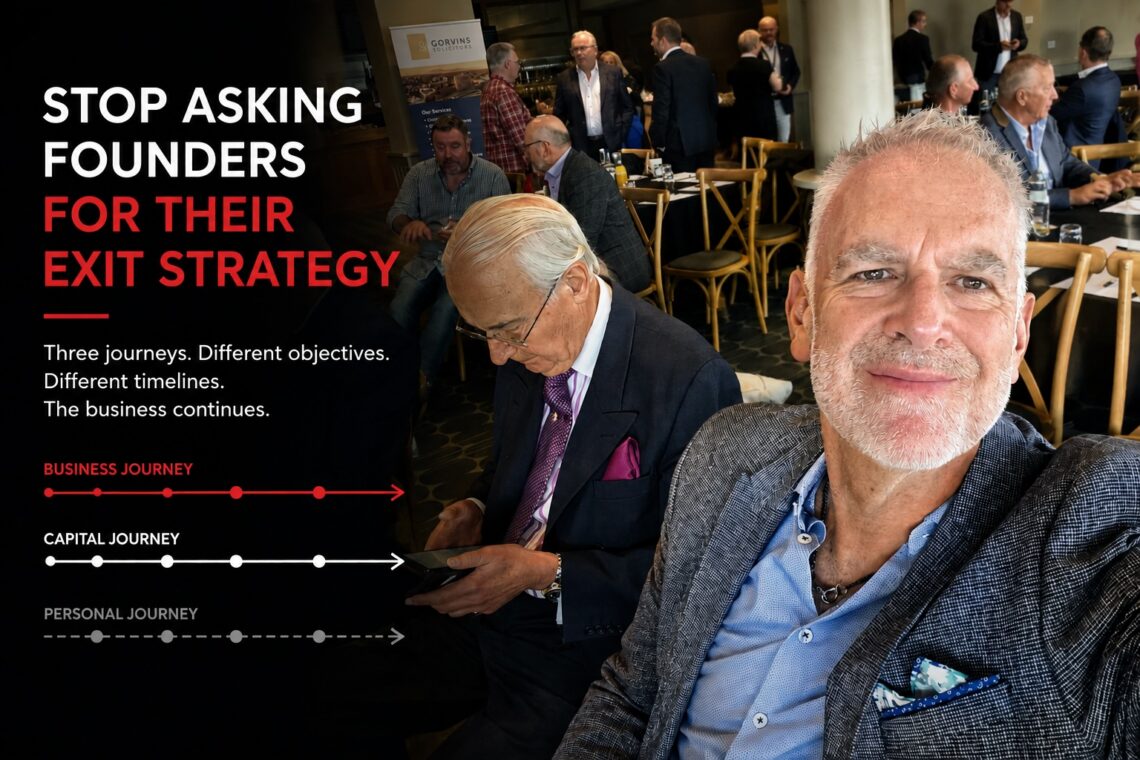
Stop Asking Founders for Their Exit Strategy
“What’s your exit strategy?”
It is one of those questions founders hear repeatedly when raising capital. It sounds perfectly reasonable, but it can cause considerable confusion because it mixes together three very different things. A founder may intend to run the business for another 20 years, the company may have a growth plan extending well beyond the investment being discussed, while the investor asking the question may need to realise a return within five, seven or ten years.
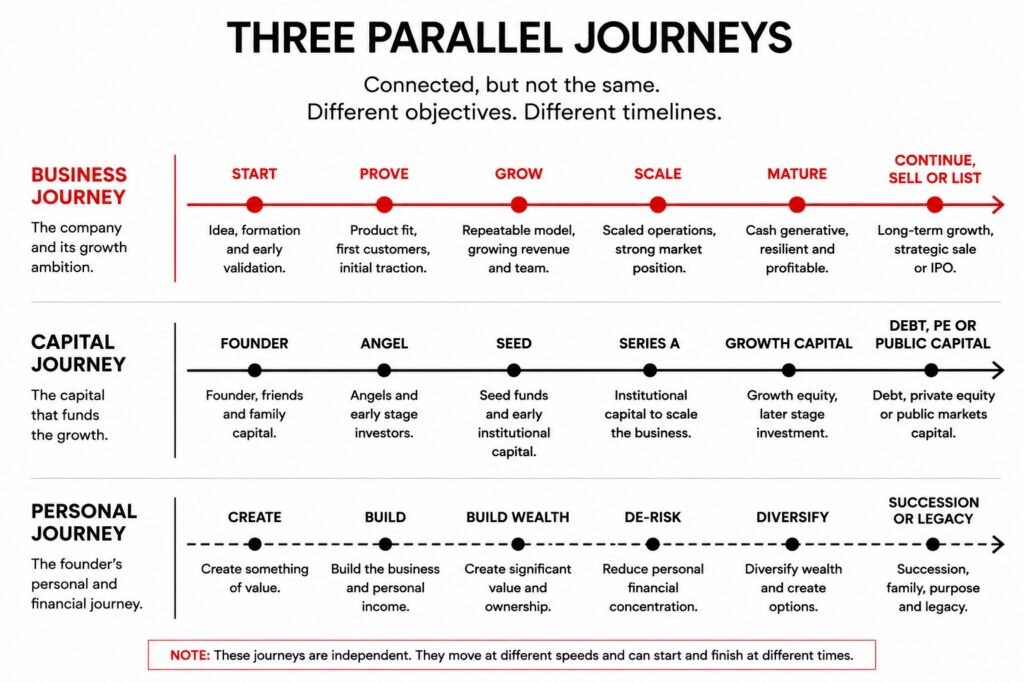
The business journey, the investor’s capital journey and the founder’s personal journey are connected, but they are not the same thing. Perhaps the starting question should therefore be: exit from what, and for whom?
The business does not necessarily exit
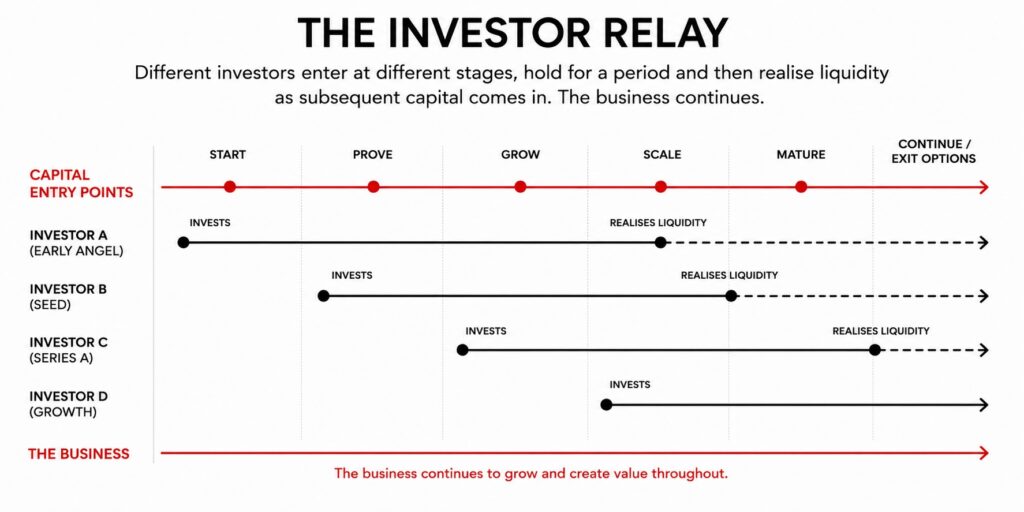
The language of “exit strategy” can make it sound as though everyone is working towards the day the company is sold. That is one possible outcome, but successful businesses can continue for decades while their investors change repeatedly.
An angel can sell some or all of their holding to a later investor. An early VC can realise its investment through a secondary transaction. One private equity investor can sell to another. The company may buy shares back, while an IPO can create liquidity for shareholders without the underlying business being sold.
Revolut provides a good example. In 2024, a secondary share sale valued the company at $45 billion and allowed employees, alumni and early investors to realise value from their shares while bringing new investors into the business. Revolut continued as the same independent private company.
Capital can exit without the company exiting.
Every investor has a clock
There is, however, a perfectly legitimate question sitting behind “what’s your exit strategy?” An investor needs to understand how their money eventually comes back and what return they might make. A VC fund has its own investors, usually Limited Partners, whose capital ultimately needs to be returned, together with whatever return the fund generates.
The current UK market illustrates the issue. British Business Bank analysis found that UK VC funds from 2002 to 2020 vintages had generated total value equivalent to 1.84 times invested capital, but only 0.69 times invested capital had actually been distributed back. Some 54% of UK fund managers surveyed still described exit conditions as poor or very poor, although 68% expected them to improve.
There can therefore be considerable value sitting inside successful companies which investors still need to turn back into cash. Rather than asking when the company will exit, the more useful question is what credible routes exist for that particular investor to achieve liquidity and over what period.
There is more than one way out
A full sale of the business is only one route. A trade sale allows another company to acquire the business, while a secondary transaction allows an existing shareholder to sell some or all of their position without selling the company. Later institutional investors can provide liquidity for earlier investors, management or the company may buy shares back, and private equity can replace one generation of investors with another.
An IPO provides another route, allowing shares to become publicly traded while the underlying company continues. Founders can also use secondary transactions to realise part of their wealth without necessarily giving up control or leaving the business.
OrganOx provides the more traditional example of an exit. The Oxford University spinout received multiple rounds of external investment before being acquired by Terumo in October 2025 for approximately $1.5 billion. BGF, which first invested in 2019 and participated in subsequent rounds, reported £175 million of proceeds and a 10 times return on its initial investment.
Revolut and OrganOx therefore demonstrate two very different outcomes. Revolut provided liquidity to existing shareholders while continuing independently. OrganOx was acquired outright. Both created an exit for investors, but only one involved the sale of the company.
Put exit inside the Capital Journey
A business may require £500,000 today, £3 million in two years and £10 million several years later. Treating those as three unrelated transactions ignores what happens between them.
Each funding round changes the Cap Table. New investors enter at different valuations, with different return expectations and investment horizons. Existing shareholders are diluted, while later rounds can create opportunities for earlier investors and founders to take some money off the table.
The Capital Journey should therefore map the likely funding requirements over several years, what each round needs to achieve, the appropriate type of capital and potential liquidity points along the way. Alongside it, the Cap Table Journeymodels what those transactions could mean for ownership, valuation and dilution.
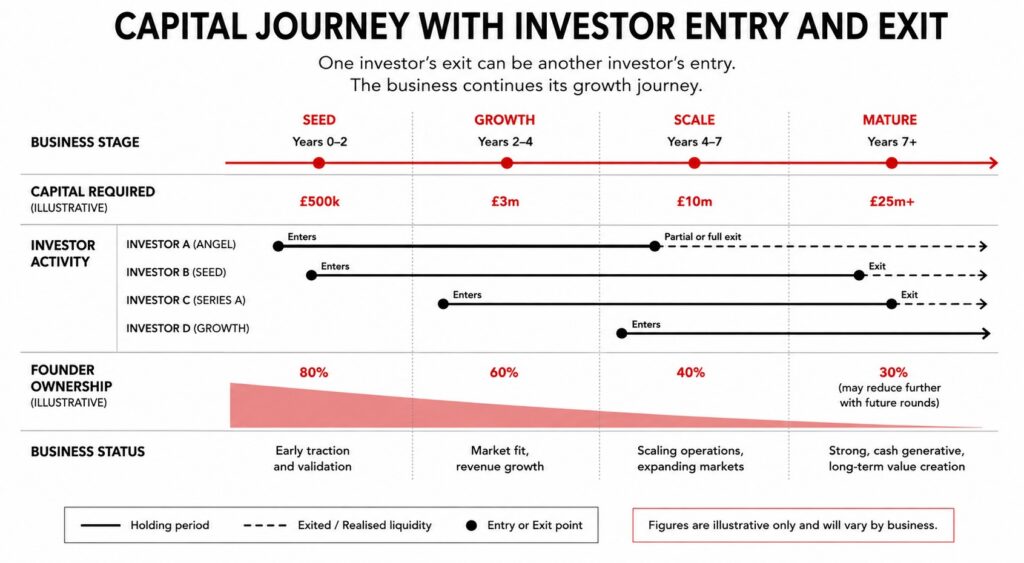
One investor’s exit can therefore be another investor’s entry point, while the company continues along its growth journey. This also changes how the first investment should be considered. A valuation or equity deal that looks attractive today can produce a very different result after several subsequent rounds, particularly if the likely Cap Table Journey has never been modelled and founder equity is progressively chipped away.
Then there is the founder’s journey
Founders can have very different ambitions. One may want to build and sell, another may want to remain CEO for decades, while another may eventually step away from management but retain significant ownership. A founder may also want to realise part of their wealth, reduce personal financial exposure and continue building the company.
As the business matures, the questions can change again. Succession, family, retirement, philanthropy, intergenerational wealth and legacy may become more important than another funding round, without requiring the business itself to be sold.
This is why the company journey and the founder’s personal journey need to be considered separately. The business strategy asks where the company is going, what capital it requires and what needs to be built to get there. The personal journey asks what the founder actually wants from the value being created, both financially and personally.
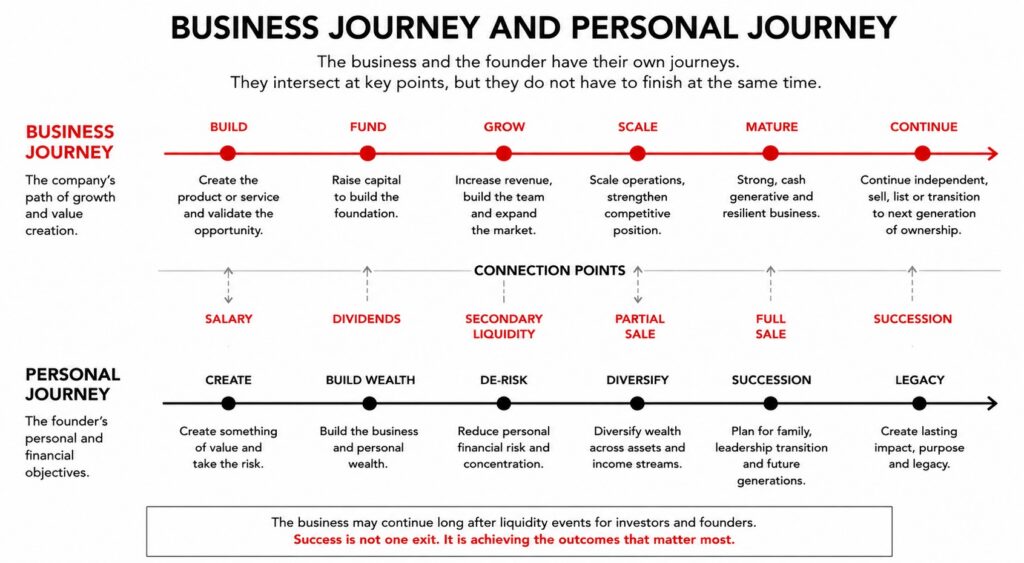
A founder can build a business worth £30 million while still having most of their personal wealth concentrated in one illiquid asset. Personal wealth, succession and family planning therefore need to start well before somebody appears with an offer to buy the company.
Three journeys, not one exit
At Kognise, the approach is increasingly to separate these three journeys. The Business Journey looks at where the company is going and what needs to be built to get there. The Capital Journey looks several funding rounds ahead, considering the amount and type of capital required, valuation, milestones, investor expectations and potential routes to liquidity.
Alongside these sits the Personal Journey, developed through the Family Legacy work, looking at what founders and directors ultimately want from the value being created, including wealth, diversification, succession and legacy. The three journeys need to work together, but they should not be confused with each other.
Change the question
Instead of simply asking a founder, “What’s your exit strategy?”, perhaps the better question is: what is the long-term ambition for the business, what Capital Journey supports it, and where are the likely opportunities for investors to realise their returns?
There is then a separate question for the founder: what do you ultimately want from the business and the value you are creating?
Those questions recognise that a company may continue through several generations of capital and ownership. They also recognise that the founder’s destination does not have to be the same as the company’s.
The business has a journey. Each investor has an entry point, return requirement and eventual route to liquidity. The founder has a personal journey which may continue long after an investor has left, and potentially long after they have stopped running the company.
The objective shouldn’t be to plan one exit. It should be to understand who needs to enter, who needs to leave, when, and where the business and its founders are ultimately trying to go.
-
An Idiot’s Guide to Funding
For most founders, raising money is a daunting process. There is a sea of investors, lenders and funds, each with their own terminology, criteria, expectations and processes. Finding money is rarely the problem. Finding the right money, from the right source, at the right time and on the right terms, is considerably harder.
There are plenty of tripwires. Raise too little and you may be back looking for money before achieving the milestones needed for the next round. Raise at an unrealistic valuation and that valuation can come back to bite you. Choose the wrong type of capital and you can restrict your options later.
Funding therefore needs to be considered as a journey. What you raise, from whom, on what terms and at what valuation should make sense not only today, but for where the business needs to be in two, three or five years.
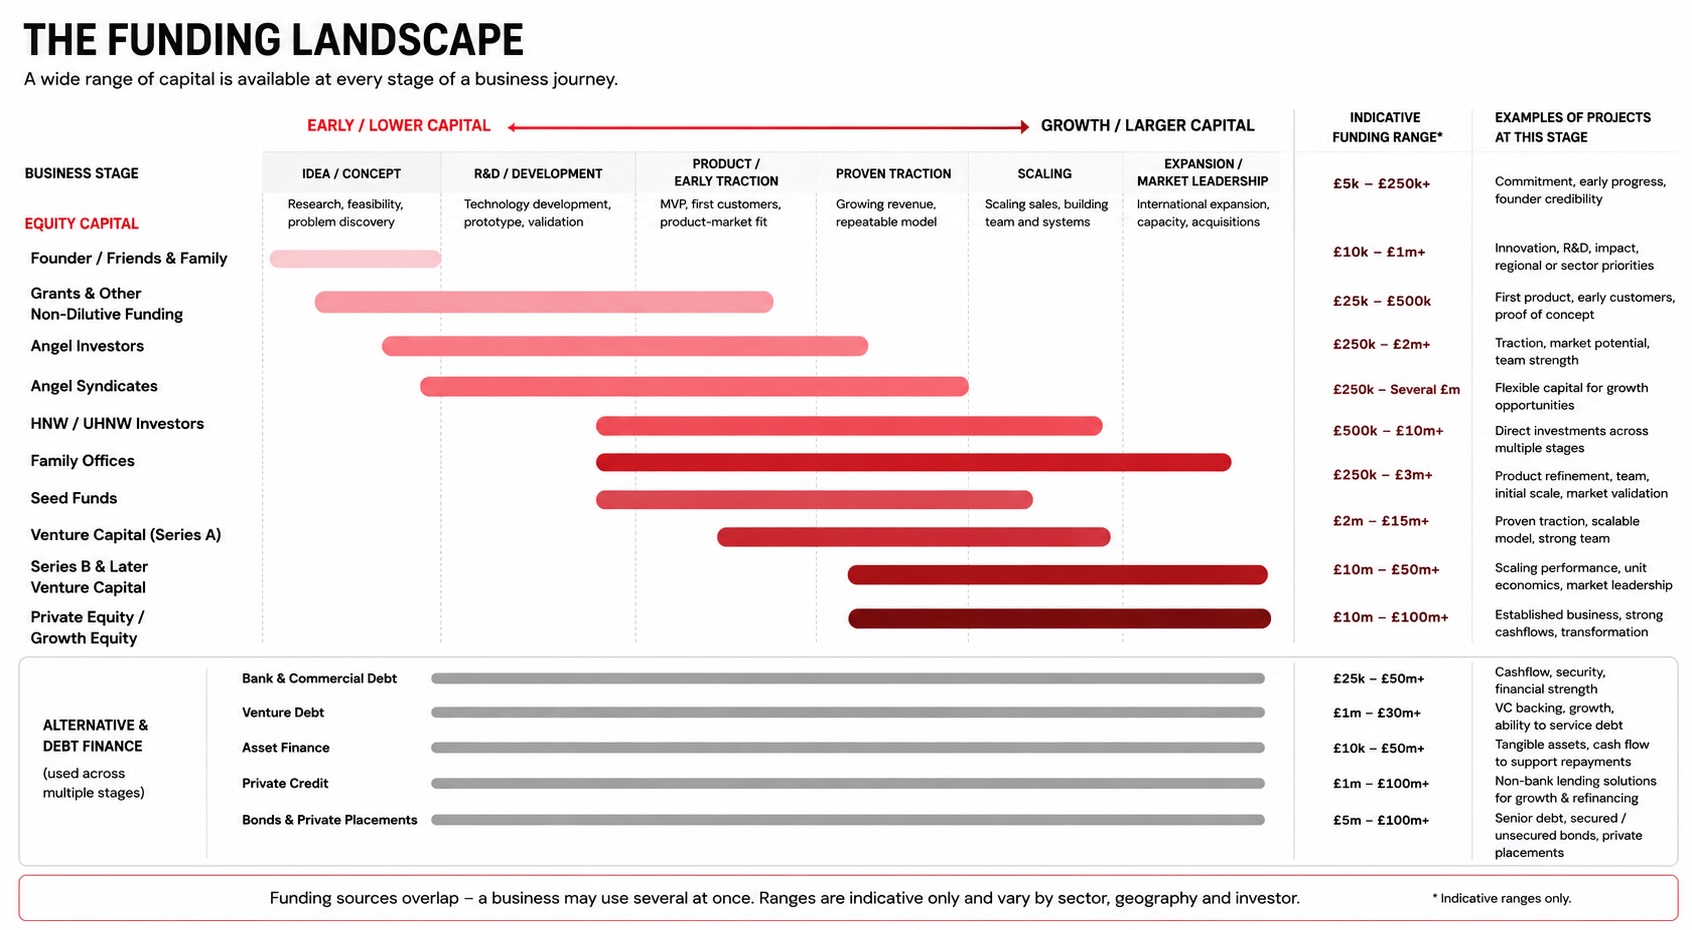
There are many variations and hybrids, but most business funding sits somewhere within the following:
- Founder funding and bootstrapping
- Friends and family
- Grants and other non-dilutive funding
- Angel investors
- Angel syndicates
- High Net Worth and Ultra High Net Worth investors
- Family offices
- Pre-seed and seed funds
- Venture capital
- Series A
- Series B and later-stage growth capital
- Corporate venture capital and strategic investors
- Equity crowdfunding
- Bank and commercial debt
- Venture debt
- Asset finance
- Private credit
- Bonds and private placements
- Growth equity and private equity
- Public markets
These aren’t rigid steps on a ladder, and a business may use several at the same time. An asset-heavy growth company, for example, could combine equity for growth and working capital with asset finance for equipment. The question is not simply what funding is available, but what combination of capital best supports the business and its next stage.
Starting at the beginning
Founder, friends and family funding usually sits at the beginning, funding development before a proposition is sufficiently mature for external investors. It offers considerable freedom, but the amount available is usually limited and the financial risk is personal.
Grants and non-dilutive funding can be attractive because the business may receive capital without surrendering equity. They commonly come with eligibility criteria, restrictions on expenditure, reporting requirements and sometimes matched funding, and are particularly relevant to areas such as innovation, R&D, sustainability and regional development.
Angel investors invest their own money and commonly appear once a business needs external capital but remains too early for many institutional funds. British Business Bank guidance puts individual angel investments broadly between £5,000 and £500,000, with larger syndicates potentially reaching around £2 million. Angels can also bring sector experience, contacts and practical support.
Angel syndicates bring several investors together, allowing larger investments while spreading individual risk. For the business, this can provide substantially more capital without immediately moving into institutional venture capital.
HNW, UHNW and family office capital
High Net Worth and Ultra High Net Worth investors occupy an interesting part of the market. Like angels, they are investing their own capital, but the sums can be considerably larger and their interests can extend from relatively early opportunities through to substantial growth transactions.
Family offices manage the wealth of one or more wealthy families. Some invest directly into businesses, while others operate much more like institutional funds. They can have greater flexibility over investment horizon, structure and stage than a conventional VC fund, although there is no particularly useful standard cheque size because their strategies and resources vary enormously.
That flexibility makes understanding the individual investor important. Knowing somebody has substantial wealth tells you very little about whether they want to invest in your business, why they would do so or what they will expect in return.
Seed and venture capital
Pre-seed is generally about turning an idea into something tangible, perhaps through research, developing an MVP, proving the technology or establishing whether a market exists.
Seed funding takes the proposition further. Capital may be used to refine the product, build the team, establish product-market fit and generate commercial traction. Investors can include angels, specialist seed funds and early-stage VCs.
The numbers vary considerably, which makes statements such as “a seed round is £500,000” fairly meaningless. In the UK, £2.1 billion was invested at seed stage during 2025. The median seed pre-money valuation was £3.2 million, compared with an average of £6 million, illustrating how easily averages can be distorted by larger transactions.
Series A usually marks a change in the conversation. The business should increasingly be able to demonstrate that the proposition works, there is genuine market demand and additional capital can accelerate growth rather than simply keep an experiment alive.
Series B and later venture rounds move further towards scaling an established growth engine. International expansion, additional capacity, infrastructure, acquisitions and market share become more relevant. The money generally becomes larger, but so does the expectation of evidence.
British Business Bank figures illustrate the range. In 2025, the average UK venture-stage deal was £5.8 million, although the median was only £1.1 million. At growth stage, the average was £14.3 million and the median £2.6 million. Averages can therefore give a misleading impression of what a typical transaction actually looks like.
Strategic investors and corporate venture capital
A strategic investor is interested in more than the financial return. Your technology, intellectual property, customers, market position or capability may complement their existing business.
Corporate venture capital can therefore bring money alongside distribution, market access, technical capability or commercial credibility. However, alignment with one industry participant can affect relationships with its competitors, so the longer-term implications need considering alongside the immediate investment.
Debt is capital too
Funding conversations often become unnecessarily focused on equity. Giving away part of the company is only one way of financing growth.
Bank and commercial debt can work where a business has sufficient cash flow and creditworthiness to service borrowing. There is no equity dilution, but the debt has to be serviced regardless of whether the growth plan performs as expected.
Venture debt can provide additional capital to venture-backed businesses without the same dilution as another equity round. It still introduces repayment obligations and normally requires sufficient backing, performance or prospects to support the lender’s risk.
Asset finance is particularly relevant where capital is required for identifiable equipment, machinery, vehicles or other productive assets. Rather than financing the whole growth requirement through equity, those assets can support a separate financing structure.
Private credit provides another source of non-bank lending, generally for larger or more established businesses. It can offer structural flexibility, but pricing, security, covenants and repayment capacity become important.
Bonds and private placements take this further. The business raises debt from investors with defined interest and repayment obligations and, depending on the instrument, security and covenants. These routes become relevant as the funding requirement and financial maturity of the business increase.
Valuation, the number that can come back to bite you
Founders understandably want the highest valuation possible because it means surrendering less equity for the same amount of money. Raise £1 million at a £4 million pre-money valuation and the investor owns 20% after the investment. Raise it at £9 million and they own 10%.
The problem comes at the next round if the business has not grown sufficiently to support that higher valuation. A new investor may refuse to accept it, creating a flat or down round, further dilution and potentially difficult consequences for existing shareholders. Valuation therefore needs to reflect both what can be achieved today and what the business can reasonably support when it next needs capital.
The highest valuation is not necessarily the best valuation.
So how do you actually find the money?
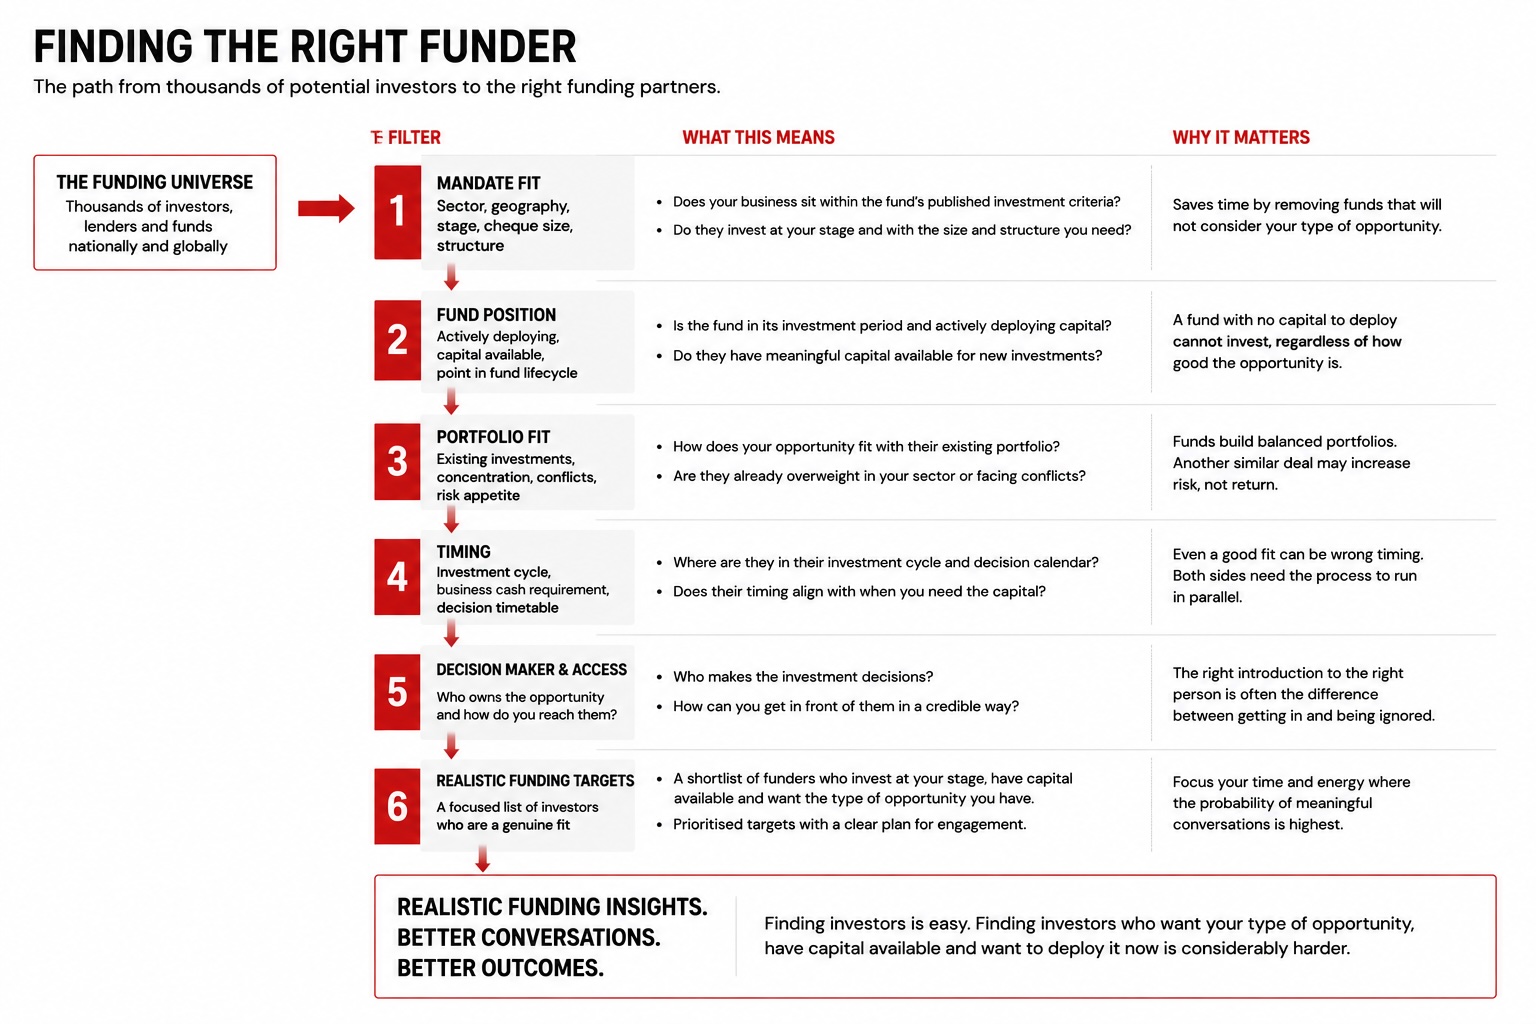
This is where fundraising becomes considerably more complicated than searching online for venture capital funds. There are thousands of potential sources of capital, spread nationally and internationally, with different requirements around sector, geography, stage, cheque size, technology, traction, structure and risk.
At the institutional level, the fund itself has a lifecycle. A newly raised fund with substantial undeployed capital is a different prospect from one approaching the end of its investment period. Funds commonly reserve capital to support existing portfolio companies through subsequent rounds, so the amount under management is not necessarily the amount available for new investments.
Portfolio composition matters too. A fund may specialise in exactly your sector but already have sufficient exposure to it, making another similar investment unattractive from a portfolio risk perspective.
Being inside a fund’s mandate does not mean the fund wants your deal.
Finding the right target therefore means understanding who is actively investing, what they want, where they are in their fund cycle, what they already hold and who makes the investment decisions.
Timing also matters. Easter, summer holidays and Christmas can slow a process when partners, investment committees, lawyers and co-investors need to be available. The funding timetable therefore needs to work backwards from when the business actually needs the cash, with sufficient contingency for a process taking longer than expected.
Getting through the door
Once suitable funders have been identified, you still have to reach them. Cold approaches can work, but trusted introductions remain valuable. The British Business Bank specifically identifies an introduction from somebody the VC trusts, such as another entrepreneur, investor, lawyer or colleague, as one of the best routes into venture capital.
Getting through the door is only the beginning. A pitch deck may lead to initial screening, management meetings, further information, due diligence, a data room and ultimately an investment committee. At every stage the funder is deciding whether the opportunity justifies progressing further.
That filtering exists because investors receive far more opportunities than they can fund. The UK market became more selective during 2025, with smaller-business equity investment falling 4% to £12.3 billion and seed and venture deal numbers falling 27% and 13% respectively. Capital became increasingly concentrated into fewer, larger transactions.
The changing front door
Historically, initial screening was often undertaken by analysts and associates reviewing pitch decks, financial information and market propositions before deciding which opportunities deserved senior attention. Increasingly, AI and automation are being introduced into sourcing, screening, analysis and due diligence.
That has advantages for investors because far more information can be processed quickly and consistently. For founders, however, it means the proposition increasingly has to survive a systematic first assessment before there is necessarily an opportunity to explain its nuances to a senior investment decision-maker.
This makes preparation more important, not less. The pitch deck, financial model, market evidence and supporting information need to tell the same story, because inconsistencies that might once have emerged during a conversation can increasingly become reasons for an opportunity not progressing.
What does a funder actually want to see?
Different capital providers have different expectations, but the underlying questions are surprisingly consistent. Is there a genuine market? Does the product solve a real problem? Will customers buy it? Can the business scale? Is the financial model credible? Is the valuation supportable? What could prevent the plan being delivered, and has management considered and mitigated those risks? Does the team have the capability to execute?
As the business progresses, evidence increasingly replaces promise. A prototype becomes a commercial product, leads become a qualified sales forecast, forecast sales become contracts and contracts become revenue. The expectations change with each funding stage because the business should have more evidence available to support its claims.
Governance also becomes increasingly important. A funder is not simply investing in the spreadsheet placed in front of them. They are investing in management’s ability to understand when reality diverges from the plan and take corrective action.
Why spray and pray rarely works
It is tempting to build a list of hundreds of investors, send everybody the same deck and hope something sticks. Poorly targeted approaches consume management time and ignore the more important question of whether the capital being pursued is actually appropriate for the business.
A database can tell you that a fund exists and perhaps what its published investment criteria are. It cannot necessarily tell you whether it has capital available today, whether its appetite has changed, whether its portfolio is already overweight in your sector or whether the relevant partner wants another investment like yours. Those are the things that determine whether an apparently perfect fund is actually a realistic prospect.
The Kognise approach
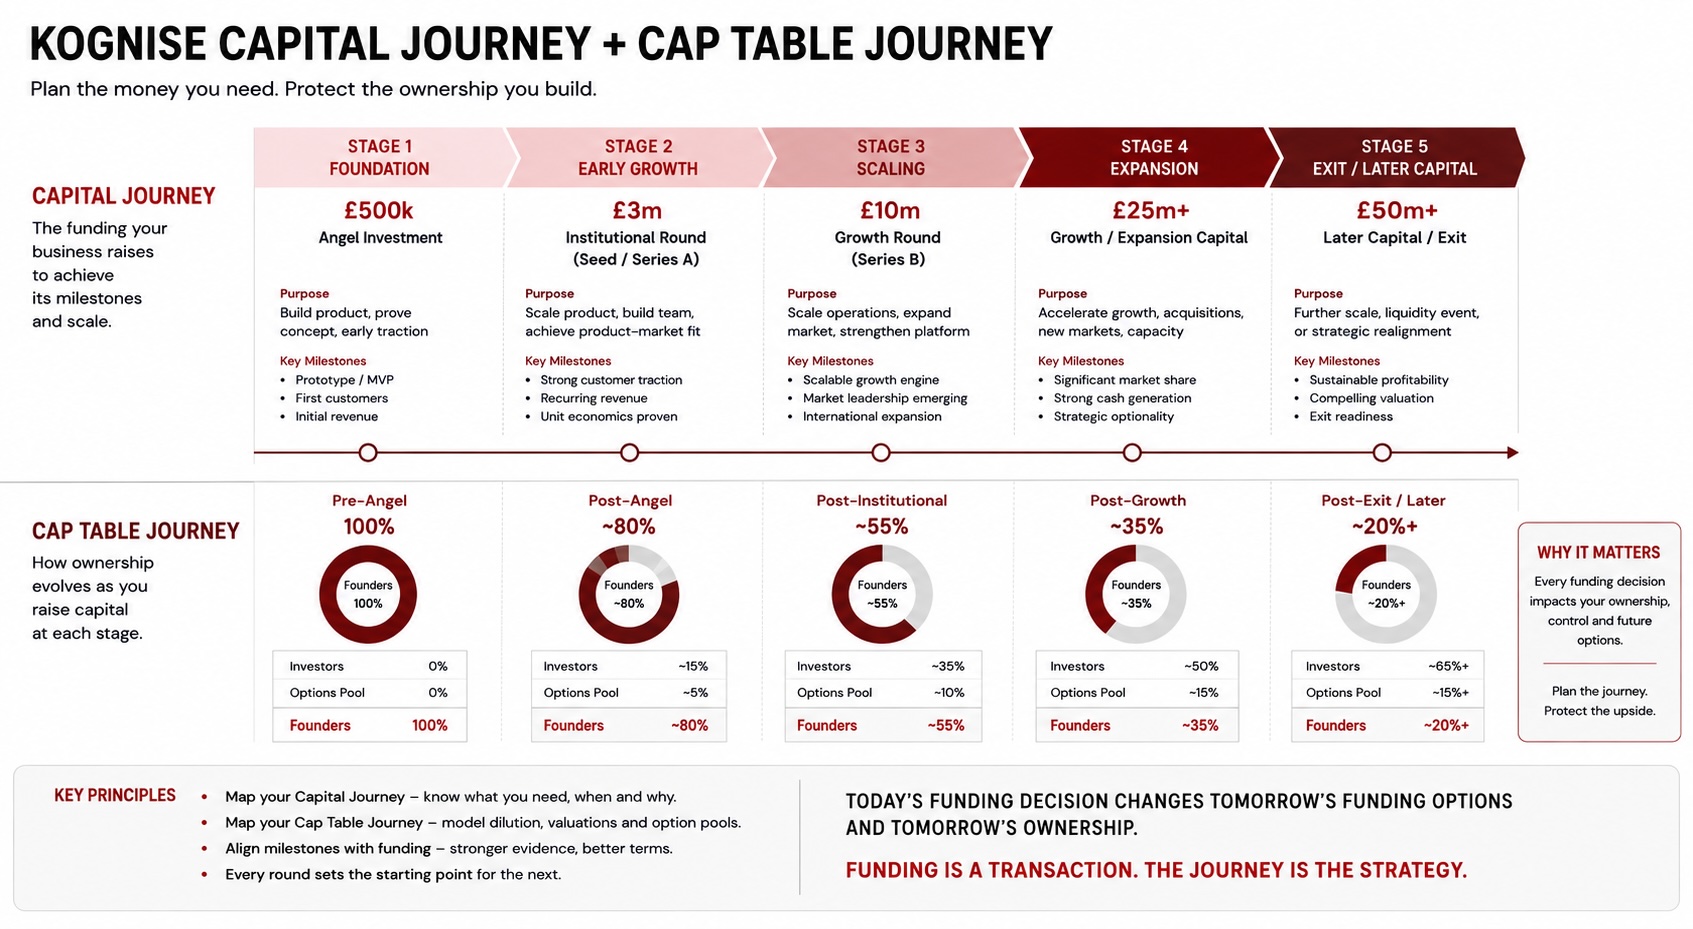
Kognise works across the capital journey, typically from HNW and UHNW investors and family offices through venture capital, Series A and Series B, alongside lenders, asset finance and other institutional capital where appropriate.
We don’t start with a database and work out how many pitch decks we can distribute. We work directly with founders, principals, boards and investment decision-makers across our funding network, which gives us an understanding of what they are actually looking for rather than simply what their published mandate says.
Those relationships work both ways. A company needs access to appropriate capital, but a funder also needs confidence that an opportunity brought to them has been properly considered and has legs. Maintaining that trust means being prepared to tell a business when it isn’t ready to raise, when the proposition needs more work or when the capital it is pursuing is wrong for its stage.
Early-stage investment inevitably involves risk, and funders know that. Their job is to understand and price that risk, build an appropriate portfolio and identify businesses where the potential return justifies taking it. Our role is to make sure the business understands what that funder will expect and is capable of supporting the proposition it puts forward.
Think beyond the next cheque
A £500,000 angel investment, a £3 million institutional round and a later £10 million growth facility are not three unrelated transactions. They form part of the same Capital Journey, with each stage changing the business that approaches the next funder.
At Kognise, we map that Capital Journey forward, looking at what funding is required at each stage, what it needs to achieve and what evidence the business must create before the next raise. Alongside it sits the Cap Table Journey, modelling how successive equity rounds, valuations and dilution affect founders and existing shareholders over time.
This matters because an investment that looks attractive in isolation can produce a very different outcome several rounds later. Without considering the likely funding journey at the outset, successive equity raises can progressively chip away at founder ownership, particularly where valuations or capital requirements do not develop as expected.
The objective is therefore not simply to get the next cheque. It is to understand the route from £500,000 to £3 million to £10 million and beyond, and structure each stage so that it supports rather than compromises what comes next.
Funding is a transaction. Becoming fundable, and remaining fundable as the business grows, is the journey.
-
Kognise and Family Legacy announce new collaboration
Kognise is delighted to announce a new collaboration with Family Legacy, bringing together our work with businesses and founders with their expertise around the personal and family side of wealth. Kognise works with companies through growth, funding, governance and delivery, including preparing for succession or exit. Family Legacy works with founders and their families on their personal objectives, wellbeing, succession, the next generation and what they ultimately want their wealth to achieve.
There is a natural connection between the two. Kognise will be able to bring Family Legacy into client engagements where personal or family considerations need to become part of the conversation. Equally, where Family Legacy identifies something that needs addressing within the underlying business, they can bring Kognise into the discussion around strategy, capital, growth, governance or exit.
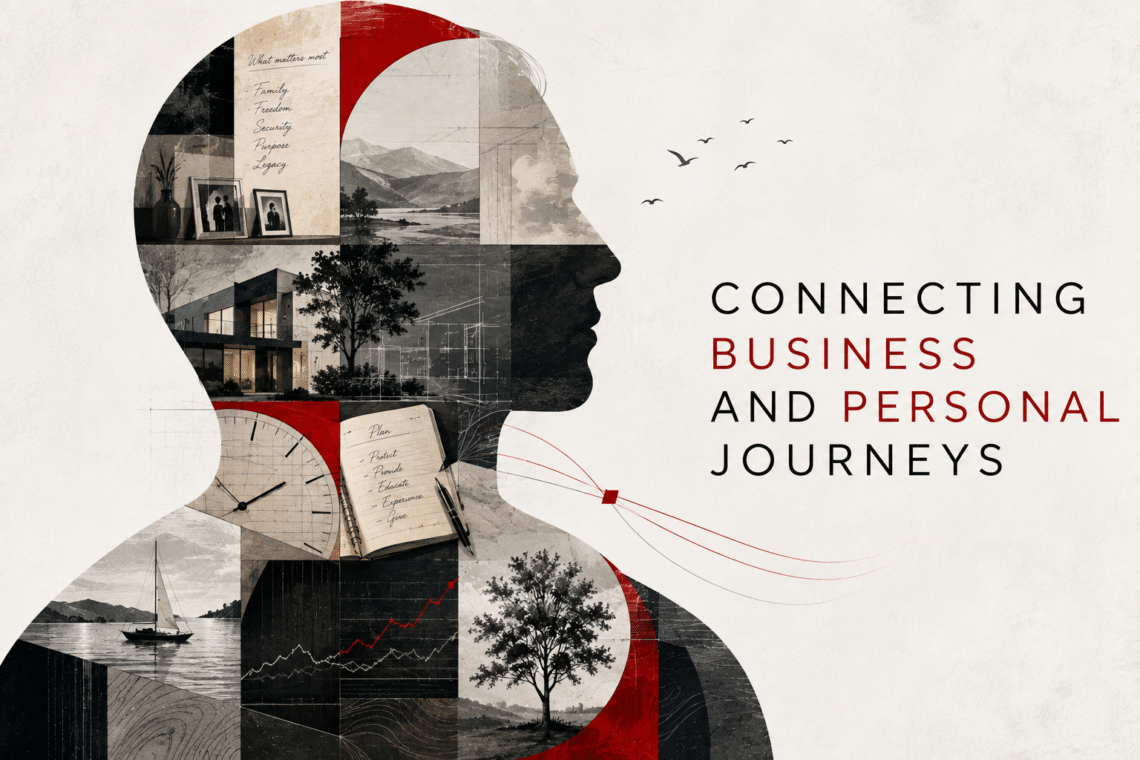
Connecting the business and personal journeys
Most advisers working with a growing business will at some point ask the founder: what’s your exit strategy? It’s a sensible question, but there’s another that often doesn’t get asked: what’s your number? If you’re building towards an exit, what does that exit actually need to deliver for you and your family, and what do you want to do afterwards?
Understanding that personal destination gives much greater context to decisions about the business, its growth, value and eventual exit. Those conversations shouldn’t wait until someone is ready to sell either. If you’re spending years building a company, your personal and family position needs consideration along the way, including making sure those closest to you are properly provided for if circumstances change.
Working with Family Legacy means we can identify those issues earlier and give clients support to work through them. Family Legacy doesn’t advise on specific regulated financial products such as investments, pensions or life assurance. Family Legacy helps clients understand what they’re trying to achieve and, where specialist advice is needed, can bring the appropriate financial, legal or other expertise into the conversation.
A relationship built over several years
The collaboration builds on relationships that go back a number of years. Tony has had an extensive career in finance including as a Founding Director of St. James’s Place Wealth Management. Orchestrated the name change from Rothschild to St. James’s Place between 1994-1997. Founder Caerus wealth, sold to Intrinsic/Quilter in 2017. Founder Legacy Group in 2017, assisting Family Offices with the retention of wealth and health. We have worked together on several projects, including running an investment fund, and along the way we’ve become good friends. I’ve wanted to find the right opportunity for us to work together again, and his work at Family Legacy creates a natural connection with what we do at Kognise.
I’ve also known Max for a number of years. He brings around 20 years of consulting experience and considerable experience in this field. Over the last couple of months, conversations between the three of us have made the opportunity to connect our respective areas of work increasingly clear.
We’re now working through how we build those connections into both businesses. I believe it will benefit clients on both sides: giving Kognise clients access to expertise around the personal and family journey, while giving Family Legacy clients access to business expertise when they need it. Ultimately, it’s about connecting what is happening in the business with what the people behind it actually want that business to achieve.
Anthony King, Kognise
“We spend a lot of time helping founders build value in their businesses. This collaboration allows us to connect that with what they actually want that value to achieve for themselves and their families.”
Tony Smith, Family Legacy
“Business success and family wealth are part of the same journey. Bringing the two together means we can start those important personal conversations much earlier.”
Max Smith, Family Legacy
“This gives us a much more joined-up approach. We can understand both the family’s longer-term objectives and the business that is creating much of that wealth.”
-
Connecting Business and Personal Journeys
Over recent months, Kognise has been expanding its portfolio of services around a simple principle: businesses need more than advice at isolated points in their development. Whether starting, scaling, restructuring, raising capital, transitioning ownership or preparing for an exit, the different parts of the journey need to connect if the strategy is going to translate into a successful outcome.
That thinking led to the introduction of Kognise Delivery Operations™, providing the coordination and delivery structure that larger corporates typically have internally but which startups, SMEs and many advisory businesses simply do not have the capacity to provide. Identifying what needs to happen is only part of the job; there also needs to be sufficient structure around the business to organise the work, maintain momentum and get it delivered.
We have also increased the sophistication of our capital work. Traditional funding tends to be approached as a transaction: identify the requirement, find the capital and complete the raise. Our Capital Journey™ looks across several years, understanding where capital is likely to be required and how different forms of funding might support each stage. That could include equity, lending, asset finance, structured funding or bonds, as well as hybrid structures combining several sources. There may be one capital event or several, but they form part of the same longer-term strategy rather than a series of disconnected transactions.
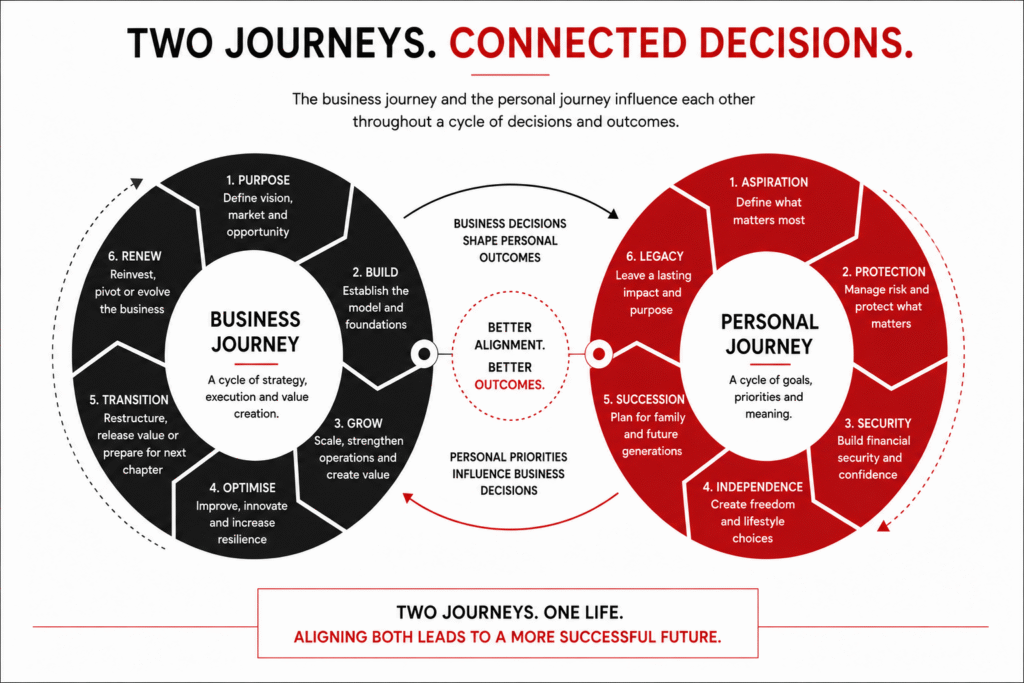
The natural extension is to consider the journey of the people behind those businesses. Their personal aspirations, responsibilities and financial objectives don’t sit independently of the commercial decisions being made, and understanding both creates a more complete picture of what a successful outcome actually looks like.
The personal journey behind the business
Every business has people behind it with their own ambitions, responsibilities and financial objectives. Those considerations can materially influence decisions about growth, investment, ownership, risk, restructuring and exit, yet they are often addressed separately from the strategy being developed for the company.
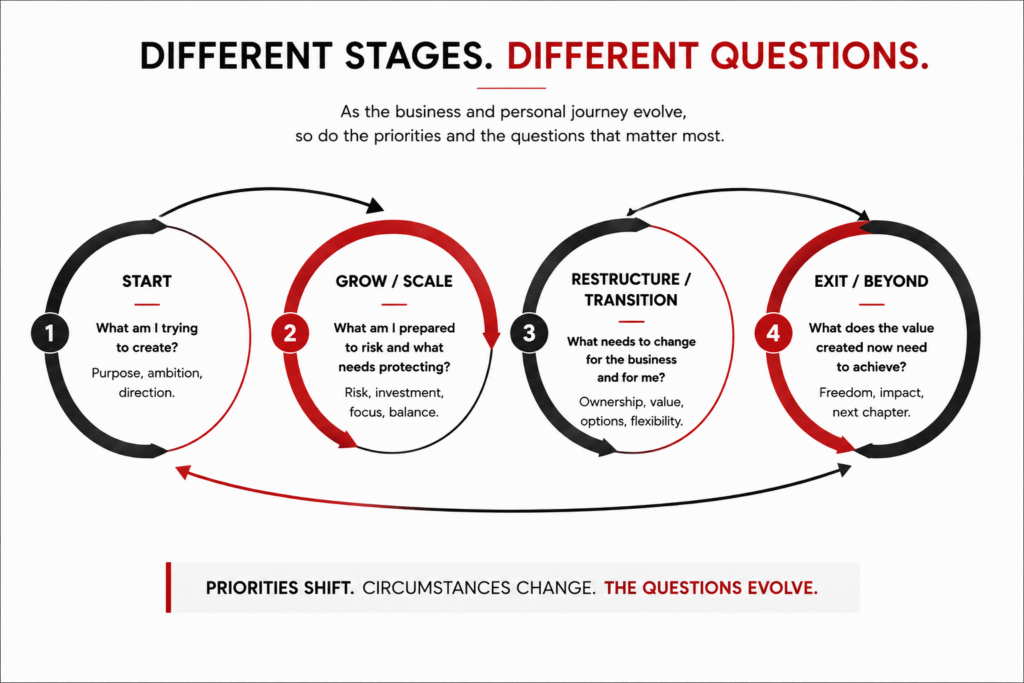
The questions will be different depending on where somebody is in that journey. A founder starting a business may be considering what they ultimately want to create, how much risk they are prepared to take and what success might look like over the longer term. Someone scaling an established company may be considering external investment, dilution, personal guarantees, family security or how much of their wealth they are comfortable having concentrated in the business.
Further along, the priorities may move towards restructuring ownership, releasing value, succession or reducing the company’s dependency on its founder. At exit, the questions change again: what financial position needs to exist once the business has been sold, what income and lifestyle need to be supported, what needs protecting and what does the next stage look like?
These considerations help define what a successful business journey needs to deliver and can influence the decisions made along the way.
Defining success beyond the business
Business is very good at putting numbers against success. Revenue, EBITDA, valuation and exit value are measurable and relatively straightforward to build into a plan, but they don’t necessarily tell us what achieving those numbers is supposed to accomplish for the people who have created the business.
A £10 million exit is a financial outcome. What matters personally is what that value needs to enable: financial independence, family security, a particular lifestyle, retirement, another business venture, intergenerational wealth or something entirely different. For someone else, selling may not be an objective at all; they may want to continue building the company while creating greater financial independence outside it.
The same principle applies much earlier. Someone creating a startup with the intention of building an asset for eventual sale is likely to make different decisions from somebody creating a business they intend to own for the next 30 years. Understanding the personal destination provides useful context for deciding what the business should become and how it should get there.
The questions change over time
The personal financial journey doesn’t suddenly become relevant when somebody approaches retirement or decides to sell. At startup, the considerations may be income, personal commitments, risk and protection. As the company develops, ownership, borrowing, external investment and the concentration of personal wealth within the business become more important. Later, the focus may move towards financial independence, succession, liquidity, family wealth and legacy.
Personal circumstances change as well. Marriage, children, illness, caring responsibilities and other significant events can alter priorities, financial requirements and appetite for risk. A business strategy that was entirely appropriate five years earlier may need to change because the objectives or circumstances of the people behind it have changed.
Introducing Values-Based Financial Planning™
Kognise is now extending its proposition via a collaboration with a highly respected and soon to be announced partner business that will help us connect business and personal journeys to incorporate specialist expertise around the personal financial journey, using an approach based on Values-Based Financial Planning™. Rather than starting with financial products, investments or pensions, the process begins by understanding the individual: what matters to them, what they want their life to look like, their responsibilities and what they ultimately want their business and accumulated wealth to enable them to achieve.
From there, financial planning can be built around those objectives. This can include lifestyle requirements, family commitments, protection and insurance, assets and liabilities, investments, pensions, financial independence, succession and longer-term legacy. The purpose is not simply to establish somebody’s financial position today, but to understand where they want to get to and what needs to be considered along the way.
For business owners, that creates an important connection. Decisions around funding, growth, ownership, restructuring and exit can have significant personal financial consequences, while personal objectives can equally influence what represents the right decision for the business.
Some of the conversations involved in Values-Based Financial Planning™ are necessarily probing and highly personal, and they sit outside the role of a Kognise adviser. The new service will therefore create two distinct and confidential relationships: Kognise will continue to work with the company on its business, delivery and capital journey, while the personal financial planning will be undertaken separately by a specialist partner.
The two sides do not need unrestricted access to each other’s information for the model to work. If an owner wants to achieve financial independence within a particular timeframe, for example, that objective may be relevant to decisions around growth, capital, ownership or exit without Kognise needing access to the detailed personal finances behind it. In the other direction, relevant business objectives can inform personal planning without unnecessarily sharing commercially sensitive company information.
A more complete proposition
There is a deliberate progression in the way the Kognise portfolio is developing. Kognise Delivery Operations™provides the structure needed to turn strategy into coordinated delivery, while the Capital Journey™ takes funding beyond the immediate transaction and considers how the business may need to be financed over time. Adding our new partnership with a specialist to deliver Values-Based Financial Planning™ brings the individual into that wider picture, connecting the creation of business value with what the people behind the business ultimately want that value to achieve.
This is relevant at any point in the business lifecycle. Someone considering their first startup will have very different requirements from an owner running a scale-up, restructuring an established company or preparing for sale, but in each case the commercial decisions and personal objectives are connected. Bringing those perspectives together should provide a better basis for making decisions without confusing the roles or compromising the confidentiality of either relationship.
We will be sharing more details re our new partner and launching the new service shortly. It represents another step in broadening the Kognise proposition around the complete journey rather than individual pieces of advice, helping clients connect the development and value of their business with the personal objectives that sit alongside it.
-
Capital Hasn’t Disappeared, It’s Become More Selective
Today I was up in Liverpool meeting the founders of a really exciting healthcare business being developed out of Liverpool University. It was one of those meetings that reminds me why I enjoy this work so much. A passionate founding team, innovative technology with genuine commercial potential and, most importantly, a willingness to think beyond simply building a product and towards building a long-term business.
Our discussion wasn’t just about raising investment. It was about building a capital strategy that could support the business over the next three, five and even ten years. Which funding instruments are appropriate at each stage? Where does equity make sense? When should lending be considered? Could strategic investors add more value than financial investors? Are there alternative funding structures that become relevant as the business matures? Those are the conversations that excite me because they help businesses think beyond the next funding round and focus instead on sustainable growth.
It also rounded off another incredibly busy week at Kognise. We’ve spent the last few days working with businesses across healthcare, life sciences, clean technology, battery storage, AI, software, retail, sustainable construction and social impact projects, while holding discussions with venture funds, family offices, ultra-high-net-worth investors, specialist lenders and organisations exploring more innovative funding structures. If there’s one thing this week has reinforced, it’s that the market is far healthier than many people believe.
The Market Says Otherwise
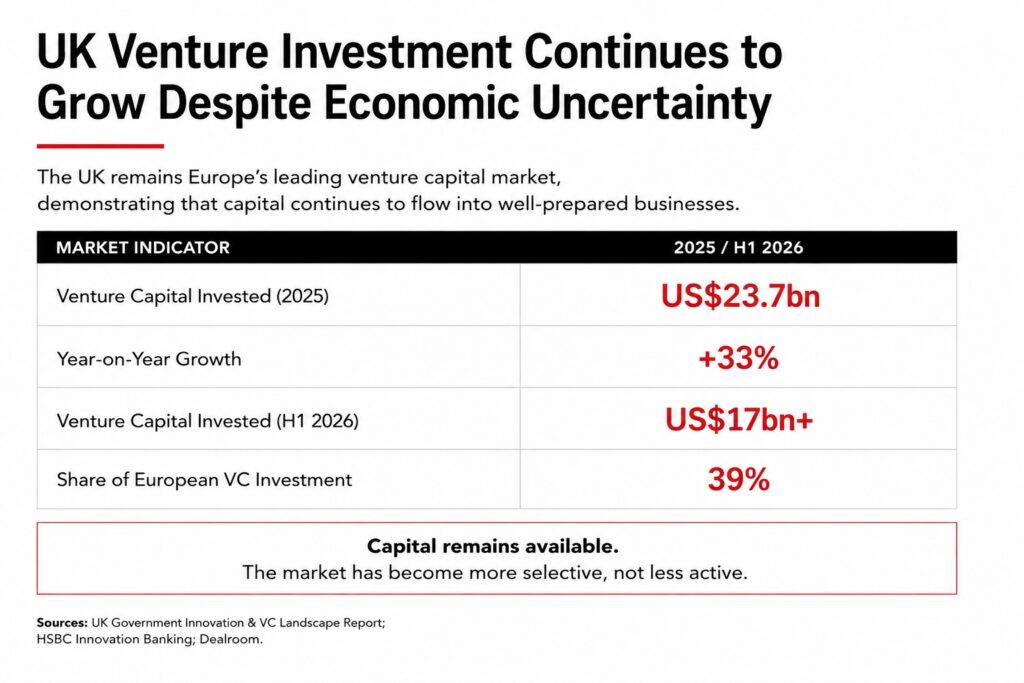
Turn on the news and it’s easy to conclude that capital has dried up, investors have disappeared and growing businesses have little chance of securing finance. The figures tell a very different story.
UK venture-backed businesses attracted around $23.7 billion of investment during 2025, representing a 33% increase on the previous year and the first significant recovery after several years of declining activity. That momentum has continued into 2026, with more than $17 billion invested during the first half of the year, leaving the UK as Europe’s largest venture capital market and attracting close to 40% of all European venture investment.
Equally significant is the amount of capital still waiting to be deployed. Across Europe, private capital funds are estimated to be holding more than €450 billion of available capital, often referred to as “dry powder”. Investors haven’t stopped investing; they’re simply becoming more selective about where that money goes.
The challenge today isn’t finding capital. The challenge is presenting businesses that are genuinely ready to receive it.
What We’re Seeing on the Ground
That changing market is exactly what we’re seeing at Kognise.
Founders are becoming increasingly aware that a single funding round is rarely enough to support an ambitious business. Equally, investors are asking more searching questions about governance, commercial models, routes to market and long-term financial planning before making investment decisions.
As a result, our conversations are changing. Rather than simply discussing how to raise investment, we’re helping businesses build capital strategies that evolve alongside their growth. Every business is different, and so is every funding solution.
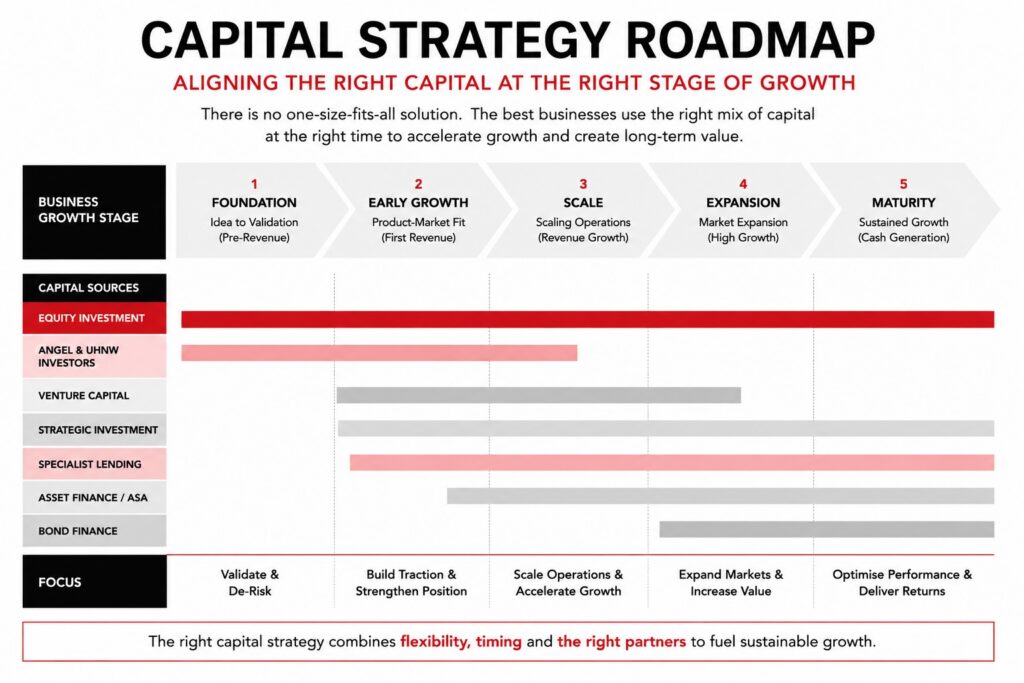
Some businesses may be best suited to ultra-high-net-worth individuals or family offices during their early stages. Others are better aligned with angel investors, venture capital or strategic corporate investment. Alongside equity, we’re increasingly discussing specialist lending, asset-backed finance, ASA structures, convertible instruments and bond programmes where they provide a better fit for the business. In many cases the answer isn’t choosing one funding route; it’s understanding how different funding instruments can work together over a number of years.
The same thinking applies to investors. We spend considerable time understanding where individual investors or funds sit within their own investment cycle, their appetite for risk, sector preferences and portfolio objectives. Matching a business to the right investor is rarely about who has the deepest pockets. It’s about finding the right long-term fit for both parties.
Why Great Businesses Are Born in Tough Markets
Economic uncertainty understandably makes founders nervous. Rising costs, tighter lending conditions and more cautious investors can easily dominate the conversation. Yet history consistently demonstrates that difficult markets often produce exceptional businesses.
The Walt Disney Company expanded during the Great Depression, offering affordable entertainment at a time when optimism was in short supply. Walmart built its reputation by delivering value during periods of economic pressure. Apple was founded during the challenging economic conditions of the 1970s before transforming multiple industries over the following decades. Closer to home, many of today’s successful UK technology businesses emerged following the financial crisis, taking advantage of changing customer behaviour and rapid advances in digital technology.
None of these businesses succeeded because markets were easy. They succeeded because challenging conditions forced them to become sharper, more disciplined and more focused on solving genuine customer problems. Difficult markets expose weak business models, but they also create opportunities for innovative businesses that can move faster than established competitors burdened by legacy systems and slower decision-making.
Today’s market feels remarkably similar. Investors may be asking harder questions, but they’re still actively looking for businesses capable of creating sustainable value.
Funding Is a Journey, Not a Transaction
One of the biggest misconceptions we still encounter is that fundraising begins with a pitch deck.
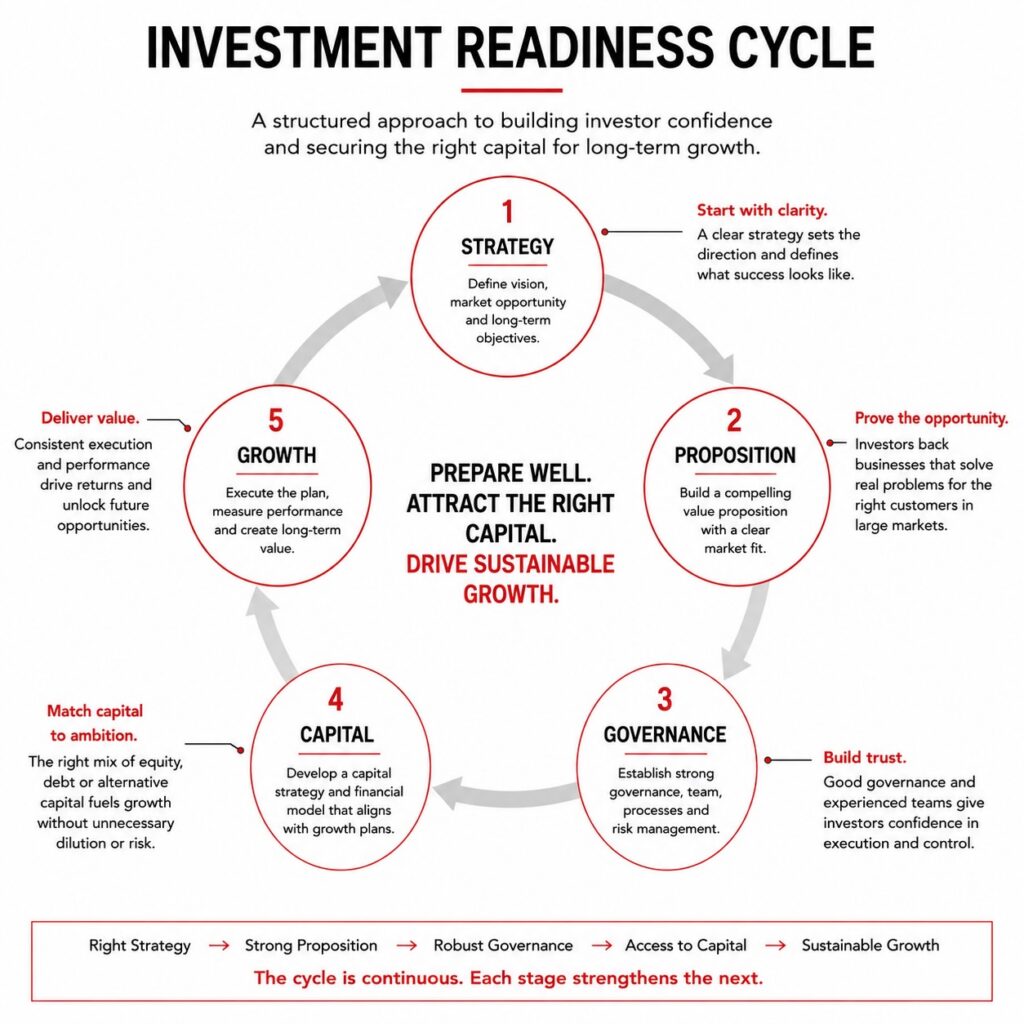
In reality, a pitch deck is simply the outcome of much earlier thinking. Before any business approaches the market, it should have a clear understanding of where it wants to be over the next three, five and ten years, the milestones it expects to reach and the capital required to achieve them.
That’s where capital strategy becomes so important.
Businesses rarely fail because they can’t raise money once. More often, they struggle because they raise the wrong type of capital, at the wrong time, or without considering how today’s decisions affect tomorrow’s opportunities. A well-designed capital strategy provides flexibility, protects shareholders where appropriate and ensures that future funding rounds become easier rather than harder.
For investors, the same principles apply. Capital isn’t simply allocated to interesting ideas. It’s allocated to businesses demonstrating commercial discipline, realistic financial planning, credible management teams and a proposition capable of delivering long-term returns. That’s why preparation has become one of the most valuable investments any founder can make before approaching the market.
Looking Ahead
As I head into the weekend, it’s difficult not to feel optimistic about the months ahead.
Yes, the market has changed. Investors are undoubtedly more disciplined than they were a few years ago, and founders need to be better prepared before seeking investment. Personally, I think that’s healthy. Good businesses deserve good capital, and good investors deserve businesses that have genuinely prepared for growth.
The conversations we’re having today are becoming less about chasing the next funding round and more about building businesses capable of thriving over the long term. That’s good news for founders, good news for investors and, ultimately, good news for the wider economy.
For all the noise surrounding economic uncertainty, this week has been another reminder that innovation hasn’t slowed, entrepreneurial ambition certainly hasn’t disappeared and capital remains available for businesses that approach growth with clarity, preparation and a well-structured strategy.
-
Every Business Needs a Capital Strategy
Choosing the right source of capital is only part of the challenge. Designing how capital supports a business throughout its journey is where real value is created.
Introduction
Almost every business reaches a point where additional capital is needed. It may be to develop a new product, enter a new market, recruit key people, acquire another business or accelerate growth. When that moment arrives, the conversation usually starts with a familiar question: where can we raise the money?
It is an understandable reaction, but it often focuses attention on the funding event rather than the business itself. The discussion quickly turns to investors, lenders or funding rounds, while much less time is spent considering whether that particular form of capital is the right fit for the objectives of the business, both today and in the years ahead.
The reality is that funding decisions have consequences long after the money reaches the bank account. They influence ownership, financial flexibility, future funding options, governance and, ultimately, the long-term value of the business. Despite this, many organisations only begin thinking seriously about capital once they have identified an immediate funding requirement.
A more effective approach is to step back before engaging with the market and ask a different question. Rather than asking how to raise the next tranche of funding, boards should first consider how the business should be financed throughout its growth and development. That is the difference between raising money and developing a capital strategy.
This distinction sits at the heart of every successful funding programme. Businesses that consistently secure the right capital are rarely those that simply become good at fundraising. They are the organisations that understand what they are trying to achieve, identify the most appropriate forms of capital to support those objectives and plan their funding requirements well before they become urgent.
The purpose of this article is to explore that difference and explain why every business, regardless of its size, sector or stage of development, benefits from having a capital strategy before approaching investors or lenders.
2. Designing Capital vs Raising Money
For many businesses, funding becomes a reactive exercise. A cash requirement is identified, a target amount is agreed and attention turns to finding an investor or lender willing to provide it. While this approach may address an immediate financial need, it often overlooks a more fundamental question: is this the right form of capital for the business?
Designing capital starts from a different position. Rather than asking how to secure a specific amount of funding, it begins by understanding what the business is trying to achieve and how those objectives should be financed over time. The discussion moves beyond the next funding event to consider the wider financial structure of the business, recognising that different activities often have different funding requirements.

Take a business planning to expand into new premises while also investing in product development. It may be tempting to include both requirements within a single equity raise because it appears to be the simplest solution. However, should long-term assets be funded through shareholder dilution if other forms of finance may be more appropriate? Equally, should innovation be financed through debt if the returns are uncertain and cash flow may not yet support repayments? The answer is rarely straightforward, which is why funding should be designed rather than simply raised.
This change in thinking also alters the conversation in the boardroom. Instead of asking, “How do we raise £2 million?”, the discussion becomes, “What is the most effective way to finance the next stage of the business?” The amount of capital may ultimately be the same, but the structure, timing and source of that capital can be very different.
The distinction may seem subtle, but it has significant implications. Businesses that approach funding as a strategic exercise are often better placed to protect shareholder value, reduce unnecessary dilution and create greater flexibility for future funding. They are designing a capital structure that supports the business over the long term rather than simply solving today’s funding requirement.
3. What Is a Capital Strategy?
A capital strategy is a long-term plan for financing a business or project. Rather than focusing on a single funding event, it considers the capital required throughout the organisation’s development and identifies the most appropriate mix of funding to support each stage of that journey.
Developing a capital strategy requires boards to answer a series of practical questions. What is the business trying to achieve? How much capital is likely to be required, and when will it be needed? Which activities are best suited to equity investment, which can be financed through lending or asset finance, and where might alternative funding structures provide a better solution? Just as importantly, how will today’s funding decisions influence future investment opportunities, shareholder value and financial flexibility?

A well-designed capital strategy also recognises that funding requirements change as a business evolves. Early-stage innovation may be best supported by one form of capital, while expansion, acquisitions or investment in physical assets may be more appropriately financed in different ways. As the business grows, new funding options become available and the balance between them may change.
This is why capital strategy should sit alongside business strategy, not behind it. If the business strategy defines where the organisation wants to go, the capital strategy defines how that journey will be financed. Together, they provide a framework that enables the board to make informed funding decisions rather than reacting to immediate financial pressures.
Before considering how these decisions are made, it is helpful to understand the principal funding instruments available and the role each can play within a wider capital strategy.
4. Understanding the Capital Toolkit
No single funding instrument is right for every business, project or stage of development. Each has different characteristics, carries different expectations and is designed to solve different commercial challenges. Understanding the fundamentals of each allows boards to make more informed decisions when designing a capital strategy.

Equity Investment involves selling a share of the business in exchange for capital. It is often the most appropriate form of funding where the business is developing new products, entering new markets or pursuing opportunities that may take time to generate returns. Equity removes the obligation to make regular repayments, but founders accept dilution in exchange for investment and expertise.
Debt Finance enables a business to borrow capital while retaining ownership. It is generally better suited to businesses with predictable revenues and the ability to service repayments. Debt can be an effective way of funding growth without diluting shareholders, although it introduces financial commitments that must be carefully managed.
Advance Subscription Agreements (ASAs) allow investors to provide funding today in return for shares that are issued at a future funding event. They are commonly used where a business needs immediate capital but both founders and investors prefer to defer the valuation until the company has reached a more mature stage.
Convertible Instruments, such as Convertible Loan Notes, begin as lending arrangements but include the option to convert into equity under agreed conditions. They provide flexibility for both businesses and investors and can bridge the gap between debt and equity where future growth is expected.
Bond Finance enables businesses to raise capital from investors in return for an agreed rate of interest over a defined period. Rather than giving up ownership, the business commits to repaying investors in accordance with the bond terms. Bonds are typically associated with more established organisations and larger funding requirements, although specialist structures are increasingly making them accessible to a wider range of businesses.
These are only some of the funding options available, but they illustrate an important principle. Each has a different purpose, a different cost and a different impact on the business. The challenge is not deciding which one is best in isolation. The challenge is understanding how they can be combined to support the wider objectives of the organisation.
5. The Right Capital for the Right Purpose
Understanding the available funding instruments is only the first step. The more important decision is selecting the right form of capital for the specific requirement it is intended to support. Too often, businesses choose a funding source first and then try to make it fit every aspect of their plans. In practice, different parts of a business often have very different funding needs.
Consider a business that is developing a new product while investing in manufacturing equipment and preparing to expand internationally. These are three separate objectives with different levels of risk, different timescales and different returns. Expecting a single funding instrument to support all three may not produce the most effective outcome. Product development may be well suited to equity investment, manufacturing equipment may be more appropriately financed through asset lending, while international expansion may require a combination of equity and working capital facilities.
This is where capital strategy becomes commercially valuable. Rather than viewing funding as a single transaction, boards begin to match each requirement with the most appropriate source of capital. That approach can help reduce unnecessary shareholder dilution, improve financial flexibility and ensure that capital is being used in the most efficient way.
There is no universal formula and no standard funding mix that applies to every organisation. The right answer depends on the business model, the stage of development, the level of commercial risk and the long-term objectives of the business. The role of a capital strategy is not to prescribe one solution, but to provide a structured framework for making informed funding decisions.
Once that principle is understood, the conversation changes again. The question is no longer which funding instrument should be used. It becomes how those different sources of capital can work together as part of a coherent long-term strategy.
6. Building a Capital Strategy
An effective capital strategy is not built by selecting a single source of funding. It is developed by looking at the business as a whole, understanding where capital will be needed over time and deciding how each requirement should be financed. This allows funding decisions to support the wider business strategy rather than simply responding to immediate cash requirements.

In practice, this means looking beyond the next investment round or lending facility. The board should understand the likely capital requirements over the coming years, identify the milestones that create value and consider how future funding options may change as the business matures. Raising every pound of capital at the earliest opportunity is not always the best solution. Equally, leaving funding until it becomes urgent can reduce choice and weaken negotiating positions.
A well-designed capital strategy also considers the balance between ownership, financial flexibility and the cost of capital. There will often be opportunities to combine different funding instruments, introducing them at the point where they are most appropriate to the business rather than relying on a single source of finance throughout its lifecycle. As commercial risk reduces and the business develops, new forms of capital may become available on more favourable terms.
The objective is not to produce a complicated funding structure. It is to build one that reflects the needs of the business, supports its strategic objectives and remains flexible enough to adapt as those objectives evolve. A capital strategy should therefore be reviewed as the business changes, ensuring that funding continues to support the organisation rather than constrain it.
Developing that strategy is not the responsibility of one individual. It is a board-level exercise that combines commercial ambition with financial planning, bringing together different perspectives to arrive at the most effective long-term approach.
7. The Boardroom Conversation
Designing a capital strategy changes the nature of the boardroom discussion. Instead of focusing on a single funding event, the conversation becomes centred on how capital can best support the long-term objectives of the business. That subtle change encourages decisions to be driven by strategy rather than by an immediate requirement for cash.

The CEO continues to play a vital role by setting the strategic direction of the business, articulating the vision and building confidence with investors, lenders and other stakeholders. However, as the discussion moves beyond fundraising and into capital strategy, the role of the CFO becomes increasingly significant. The financial model is no longer simply a forecasting tool. It becomes the framework that allows different funding structures to be tested, future capital requirements to be assessed and the implications of alternative funding strategies to be understood.
This is where an experienced CFO adds considerable value. By modelling different scenarios, the board can explore the effect of shareholder dilution, debt servicing, investment timing and future funding requirements before committing to a particular course of action. Rather than asking how to raise a specific amount of capital, the discussion becomes one of designing a funding structure that supports the business throughout its development.
The result is a more informed boardroom conversation. Decisions are based not only on the availability of capital today, but on how those decisions influence future growth, financial flexibility and shareholder value. That is one of the key differences between raising money and developing a capital strategy.
The quality of those discussions ultimately depends on the quality of the preparation. Before engaging with investors or lenders, businesses need more than a compelling proposition. They need the strategic, commercial and financial evidence to demonstrate that their capital strategy is both credible and deliverable.
8. Preparing for Capital
Once a capital strategy has been established, attention turns to preparing the business for engagement with investors, lenders or other providers of capital. Many organisations underestimate this stage, assuming that a strong idea or a compelling presentation will be enough. In reality, different providers of capital will expect different levels of evidence, but all will want confidence that the business has a credible plan and the capability to deliver it.
Preparation begins with clarity of strategy. Funders need to understand not only what the business intends to achieve, but why capital is required, how it will be deployed and what value it is expected to create. That strategic narrative must then be supported by robust financial modelling, realistic assumptions and a clear understanding of the risks involved.
Commercial evidence is equally important. Depending on the stage of the business, this may include customer traction, a validated sales pipeline, market demand, contracts, intellectual property or other evidence that supports the investment case. Governance also becomes increasingly significant as funding requirements grow, with greater scrutiny of reporting, decision-making, shareholder arrangements and the overall maturity of the organisation.
The level of due diligence will naturally vary depending on the type of capital being sought. An equity investor, a lender and a bond investor are unlikely to ask exactly the same questions because they are assessing different types of risk. Businesses that recognise this are better able to prepare for those conversations and present information that is relevant to the funding being pursued.
Preparing for capital is therefore about much more than assembling documents. It is about demonstrating that the business understands its own strategy, has selected the right funding approach and is ready to execute the next stage of its development. That preparation also helps avoid many of the mistakes that businesses make when seeking external capital.
9. Common Mistakes
Most businesses don’t make poor funding decisions because they lack ambition or commercial ability. More often, they make them because they approach funding as an isolated event rather than as part of a wider capital strategy. The consequences may not become apparent until much later, when additional capital is required or the business finds itself constrained by decisions made several years earlier.

One of the most common mistakes is treating every funding requirement in the same way. Equity is often seen as the default solution, even where other forms of capital may be more appropriate. While equity is an invaluable source of growth capital, using it to finance every aspect of a business can result in unnecessary shareholder dilution and reduce flexibility in future funding rounds.
Another frequent mistake is focusing only on the immediate requirement. Businesses understandably concentrate on the capital they need today, but rarely step back to consider how today’s decisions will affect tomorrow’s options. A funding structure that solves an immediate challenge may not be the most effective way of supporting the next stage of the business.
Preparation is another area where organisations often underestimate the work involved. Many boards invest significant time refining presentations for investors while spending much less time testing financial assumptions, validating commercial forecasts or considering how different providers of capital will assess the opportunity. A strong presentation may secure a meeting, but it is the quality of the underlying business that ultimately secures investment.
None of these mistakes are inevitable. They are usually the result of businesses concentrating on the mechanics of raising capital rather than taking the time to design a capital strategy that supports their wider objectives. The organisations that consistently achieve better funding outcomes are rarely those that tell the best story. More often, they are the ones that have done the thinking before they enter the room.
10. The Kognise Approach
At Kognise, we believe that capital should be designed, not simply raised. Every business has different ambitions, different challenges and different funding requirements, so there is rarely a single solution that fits every situation. Our role is to help boards understand the options available, design an appropriate capital strategy and prepare the business to engage with the right providers of capital at the right time.

Our work typically begins with the business strategy rather than the funding requirement. We seek to understand what the organisation is trying to achieve, how that ambition translates into capital requirements and what combination of funding instruments is most appropriate. That process considers not only the immediate requirement, but also how future funding is likely to evolve as the business develops.
Once a capital strategy has been established, we work with management teams to strengthen the evidence that supports it. This may include reviewing financial models, challenging commercial assumptions, refining the investment proposition and ensuring the business is prepared for the level of scrutiny that different providers of capital will apply.
Only when those foundations are in place does the discussion move to engaging with investors, lenders or other funding partners. By approaching funding in this way, businesses are better positioned to secure capital that supports their long-term objectives rather than simply addressing an immediate financial need.
The outcome is not just a successful funding exercise. It is a capital strategy that provides the board with greater confidence, improves decision making and creates a stronger platform for sustainable growth.
11. Conclusion
Every business will, at some stage, need access to capital. The question is not whether funding will be required, but whether that funding will be approached as a series of individual transactions or as part of a considered capital strategy.
The organisations that achieve the strongest long-term outcomes rarely view funding in isolation. They understand what they are trying to achieve, select the most appropriate forms of capital to support those objectives and recognise that their funding requirements will evolve as the business grows and changes. Capital becomes an enabler of strategy rather than simply a solution to a short-term financial requirement.
There is no single formula that applies to every business, nor is there one funding instrument that provides every answer. Equity, debt, bonds, ASAs and other forms of capital each have an important role to play when they are applied to the right requirement, at the right time and for the right reason.
Perhaps the most important shift is one of mindset. Instead of asking, “How do we raise the money?”, boards should begin by asking, “How should this business be funded?” The answer to that question forms the foundation of a capital strategy and, ultimately, a stronger and more resilient business.
-
Kognise Delivery Office (KDO)
Kognise has launched the Kognise Delivery Office (KDO), a new service designed to strengthen the way investment and growth engagements are delivered.
The KDO was developed in response to a challenge seen across almost every client engagement. Founding teams are often highly capable but extremely busy. Information becomes fragmented, meetings drift, actions are missed and momentum slows. Valuable time is spent coordinating people instead of progressing the investment.
The Kognise Delivery Office provides a structured delivery framework from the first client conversation through to investment. It manages client onboarding, readiness reviews, data rooms, project planning, governance, deliverable tracking, investor coordination and engagement management, ensuring every part of the process remains organised and moving towards a successful outcome.
The service is built around proven templates and delivery frameworks, creating a consistent approach across every engagement while allowing advisory specialists to focus on strategic, commercial and technical work.
The launch of the KDO also introduces a new delivery model across Kognise engagements. Rather than providing advice alone, Kognise now combines advisory services with structured governance and delivery management, giving founders a single engagement that supports both strategy and execution.
The Kognise Delivery Office is available immediately as part of managed client engagements.
To learn more about the service, read the full article:
-
Kognise Delivery Office (KDO)
Service Definition
Preparing a business for growth, investment or strategic change is a complex undertaking involving multiple specialist disciplines, stakeholders and interdependent workstreams. Commercial strategy, capital planning, financial modelling, valuation, governance, legal structuring, technical due diligence and investor engagement all contribute to a successful outcome. However, delivering a successful outcome depends upon more than the quality of those individual disciplines; it depends upon coordinating them within a structured delivery programme.
Successful investment programmes require more than good advice. They require disciplined delivery.
Many larger organisations recognise project delivery as a professional discipline in its own right. They support strategic initiatives through dedicated project management, programme management, governance, quality and operational delivery functions that provide structure, coordination and control while allowing subject matter experts to concentrate on the areas where they create the greatest value.
Most SMEs, scale-ups and founder-led businesses do not have access to these capabilities. As a result, founders and leadership teams are often expected to coordinate complex investment programmes while simultaneously running the business. They must organise information, manage governance, coordinate advisers, respond to investor requests and maintain programme momentum, despite having little prior experience of undertaking these activities.

A capability comparison illustrating the differences between a large enterprise and an SME/scale-up, highlighting the specialist capabilities required to deliver a successful growth or investment programme.
The challenge does not stop with the client. Many boutique advisory firms and smaller investment advisers also rely upon senior specialists to coordinate engagements alongside their advisory responsibilities. Whilst those advisers possess significant commercial, financial, legal or technical expertise, project delivery is a different professional discipline centred around planning, coordination, governance, stakeholder management, information management and programme control.
The consequence is often an inefficient deployment of specialist expertise. Highly experienced advisers spend valuable time coordinating activities that neither require nor benefit from their specialist knowledge, increasing delivery costs while reducing the time available for the activities that genuinely create value for the client.
The Kognise Approach
Kognise applies the delivery disciplines commonly found within larger organisations to every client engagement. Rather than treating project coordination as an administrative activity or expecting advisers to manage programme delivery alongside their technical responsibilities, Kognise recognises delivery as a specialist capability in its own right and embeds it into every engagement.
Every Kognise engagement is delivered as a managed project rather than an open-ended consultancy assignment.
Each engagement is established with defined objectives, agreed scope, structured workstreams, measurable milestones, governance, quality review points and completion criteria. This creates a disciplined delivery framework that provides both the client and the advisory team with visibility, accountability and a structured route from engagement initiation through to completion.
This capability is delivered through the Kognise Delivery Office (KDO). The KDO is not an administrative support function and it does not replace specialist advisers. It is the operational delivery capability responsible for coordinating the engagement, maintaining project discipline and ensuring that every workstream progresses in a structured, efficient and predictable manner.

Diagram showing the Client, Engagement Lead, Kognise Delivery Office (KDO) and specialist advisory disciplines, illustrating how the KDO coordinates delivery while the Engagement Lead owns the client relationship and advisers own their technical work packages.
Purpose
The purpose of the KDO is to provide the operational capability required to deliver complex growth, investment and strategic change programmes efficiently and consistently. It coordinates the activities of the client, the Kognise advisory team and external specialists, ensuring that information is organised, governance is maintained, project activities remain aligned and agreed deliverables are completed within an established project framework.
By separating project delivery from specialist advisory disciplines, Kognise enables each profession to focus on its own area of expertise. Commercial, financial, legal and technical advisers concentrate on developing recommendations and delivering specialist outputs, while the KDO provides the coordination, governance and operational discipline that brings those disciplines together into a single integrated engagement.
Delivery Model
Every engagement is led by an Engagement Lead, who remains responsible for the client relationship, commercial oversight and overall direction of the engagement. Working alongside the Engagement Lead, the KDO coordinates the operational delivery of the project across all specialist disciplines, maintaining the delivery plan, managing dependencies, coordinating stakeholders and ensuring that progress remains aligned to the agreed objectives.
The Engagement Lead owns the relationship. The KDO owns the delivery.
Specialist advisory disciplines retain responsibility for the quality and technical content of their respective work packages. The KDO does not supervise those disciplines or replace their expertise; instead, it provides the framework through which they operate, coordinating activities, managing governance, tracking progress and maintaining momentum throughout the engagement.

A lifecycle diagram illustrating the journey from Discovery through Gap Analysis, Project Definition, Delivery, Investor Engagement, Transaction Completion and Post-Transaction Governance.
Scope of the KDO
Project Initiation
The KDO establishes the operational framework for the engagement by confirming project objectives, defining scope, agreeing workstreams, developing the delivery plan and establishing governance, reporting arrangements and key milestones.
Discovery & Gap Analysis
The KDO assesses the client’s current level of readiness by identifying existing documentation, reviewing information structures, assessing governance maturity and establishing what information already exists. Working against the agreed project framework, it identifies capability gaps, prioritises activities and produces the structured delivery plan that guides the engagement.
Project Planning & Delivery
The KDO maintains the master project plan throughout the engagement, coordinating workstreams, monitoring actions, tracking milestones and dependencies, managing delivery risks and maintaining regular project reporting. Where priorities or scope evolve, the KDO coordinates those changes through an agreed governance process while maintaining visibility of the overall programme.
Information Management
The KDO establishes and maintains the information environment required to support the engagement. This includes structured filing systems, project documentation, document registers, working and investor data rooms, version control and document collection. Before specialist review takes place, the KDO ensures that information is complete, current and organised, allowing advisers to focus on reviewing content rather than searching for it.
Operational Coordination
The KDO coordinates the operational activities that keep the engagement progressing efficiently. This includes diary management, meeting scheduling, agenda preparation, action tracking, communication coordination, workshops, project logistics and delivery planning across all workstreams.
Investment Process Delivery
As an engagement moves into investor activity, the KDO coordinates the operational aspects of the investment process. This includes confidentiality documentation, investor meetings, investor data rooms, information requests, due diligence workflows, document execution, signature processes and post-meeting action management, ensuring that the transaction progresses in an organised and controlled manner.
Governance
The KDO maintains the governance framework throughout the engagement by coordinating governance meetings, reporting cycles, governance calendars, project records and audit trails. Where appropriate, it also supports the transition from transaction completion into ongoing governance and reporting arrangements.

A process framework illustrating the KDO’s core responsibilities: Planning, Coordination, Information Management, Governance, Communication, Delivery Control, Reporting and Change Management.
Client Benefits
The KDO gives growing businesses access to a delivery capability that is normally associated with much larger organisations. Rather than expecting management teams to build project management, governance and programme coordination functions internally, or relying on specialist advisers to undertake delivery management alongside their technical disciplines, clients gain access to a dedicated professional capability designed specifically for complex growth and investment programmes.
Enterprise-level delivery capability without enterprise-level overhead.
The result is a structured engagement with clearly defined objectives, milestones and deliverables, better organised information, stronger governance, more efficient deployment of specialist expertise and greater visibility of progress throughout the engagement. Clients benefit from a disciplined and repeatable route from project initiation through to successful completion while maintaining confidence that every workstream is progressing in a coordinated and professionally managed manner.

A comparison framework showing how a conventional advisory engagement differs from the Kognise model, highlighting the role of the KDO, structured project delivery, governance and integrated workstreams.
Guiding Principle
Kognise believes that the most successful growth and investment programmes combine specialist expertise with professional project delivery. The KDO integrates project management, governance, operational coordination and information management into every engagement, giving growing businesses access to the same level of delivery discipline and organisational capability that larger organisations routinely apply to their most important strategic initiatives.